Where Uncertainty is the killer: Jakarta Traffic Edition

So I’m currently in Jakarta. I got here on Friday evening, though we decamped to Yogyakarta for the weekend, and saw Prambanan and Borobudur. The wife is doing her mid-MBA internship at a company here, and since it had been a while since I’d met her, I came to visit her.

And since it had been 73 whole days since the last time we’d met, she decided to surprise me by receiving me at the airport. Except that she waited three and a half hours at the airport for me. An hour and quarter of that can be blamed on my flight from Kuala Lumpur to Jakarta being late. The rest of the time she spent waiting can be attributed to Jakarta’s traffic. No, really.

Yesterday evening, as soon as we got back from Yogyakarta, we went to visit a friend. Since this is Jakarta, notorious for its traffic, we landed up at his house straight from the airport. To everyone’s surprise, we took just forty minutes to get there, landing up much earlier than expected in the process.

So I’ve described two situations above which involved getting to one’s destination much ahead of schedule, and attributed both of them to Jakarta’s notorious traffic. And I’m serious about that. I might be extrapolating based on two data points (taking into the prior that Jakarta’s traffic is notorious), but I think I have the diagnosis.

The problem with Jakarta’s traffic is its volatility. Slow-moving and “bad” traffic can be okay if it can be predictable. For example, if it takes between an hour and half to hour and three-quarters most of the time to get to a place, one can easily plan for the uncertainty without the risk of having to wait it out for too long. Jakarta’s problem is that its traffic is extremely volatile, and the amount of time taken to go from one place to the other has a massive variance.

Which leads to massive planning problems. So on Friday evening, the wife’s colleague told her to leave for the airport at 7 pm to receive me (I was scheduled to land at 10:45 pm). The driver said they were being too conservative, and suggested they leave for the airport at 8, expecting to reach by 10:30. As it happened, she reached the airport at 8:45, even before my flight was scheduled to take off from KL! And she had to endure a long wait anyways. And then my flight got further delayed.

That the variance of traffic can be so high means that people stop planning for the worst case (or 95% confidence case), since that results in a lot of time being wasted at the destination (like for my wife on Friday). And so they plan for a more optimistic case (say average case), and they end up being late. And blame the traffic. And the traffic becomes notorious!

So the culprit is not the absolute amount of time it takes (which is anyway high, since Jakarta is a massive sprawling city), but the uncertainty, which plays havoc with people’s planning and messes with their minds. Yet another case of randomness being the culprit!

And with Jakarta being such a massive city and personal automobile (two or four wheeled) being the transport of choice, the traffic network here is rather “complex” (complex as in complex systems), and that automatically leads to wild variability. Not sure what (apart from massive rapid public transport investment) can be done to ease this.
On startups, headless chicken, trend following and execution

So I recently told someone, “I don’t like your business idea. It’s too brick and mortar for me”. By publicising that I said this, I’m probably ruling myself out of a large number of possible job openings, if I want to get interested in those things. For the buzzwords nowadays in the Indian startup world are implementation, delivery, execution and getting one’s hands dirty. By professing a dislike for “brick and mortar”, I’m basically declaring myself to be a sort of a misfit for the Indian startup world.

Traditionally, things like what I’ve mentioned above – implementation, execution, delivery, etc. have never been sexy. They’ve basically been the necessary work that has had to be done to get full mileage out of one’s sexy work. The sexy work has traditionally been getting ideas, solving problems, negotiating, cutting deals and all such. And in the traditional model the unsexy work has gotten outsourced to the underlings and the less capable and to “Bangalore”.

But then this model wasn’t very sustainable. A bank I used to work for insisted that quants code their own trading algorithms, arguing that the transaction cost of explaining the algorithm to a specialist coder was significantly higher than the cost of coding it themselves. Recently, an interview with Jay Parikh of Facebook revealed that they’ve stopped bifurcating employees as those that do “day to day work” and those that work on “breakthrough ideas”.

Basically, companies started figuring out that the necessary but unsexy work was actually much more critical than they had imagined, but it was hard to motivate people to do a good job of them. So the next natural step was to play up the roles that had traditionally been unsexy. So execution became part of the mantra. Corporate leaders and gurus would talk about how they were successful due to an extreme focus on “rolling up their sleeves and getting their hands dirty”. And it seems to have worked.

Rather, I think it has worked too well. Implementation and execution has been played up so much that nobody can talk much about the kind of work that used to be sexy. So people don’t talk about ideas any more – the consensus seems to be that ideas are cheap and anyone can generate them, and what matters is only execution. Venture capitalists talk about execution, too, and of investing in companies based on the execution capabilities of the founders. And having invested, they drive their investees to simply “execute away”, and get things done.

I don’t have too many closely observed data points to corroborate this, but my reading of the Indian startup scene is that it is full of headless chicken. The focus on execution is so extreme, and the push from founders and venture capitalists in that direction so strong, that it appears that people have stopped thinking any more. And (again, this might appear speculative, and it is, for I don’t have much data to back this up) it appears that such sectors are headed for a kind of equilibrium where extreme execution is the norm, and people who like to deliberate and think before acting are getting weeded out.

I’m not saying that we should not execute, or give execution its due. All I’m saying is that we’ve gone too far in that direction, to a state where thinking might actually be penalised. And it is this bit that needs to be kinda “rolled back”. But then who will execute this roll-back?

Books and Kindle Singles

Recently I started re-reading Vikram Chandra (the novelist and Berkeley academic)’s book “Mirrored Mind”, which has been published in the US as “Geek Sublime”. I hadn’t read it earlier – I had only read the Kindle sample and then discarded it, and I recently decided to pick it up from where I had left off.
In fact, that was hard to do, so I decided to start from the beginning once again, and so went through the introduction and preface and acknowledgements and all such before diving into the book again. This time I liked it better (not that I hadn’t liked it the first time round), and so decided to buy the full book. But somewhere midway through the full book, I lost enthu, and didn’t feel like reading further. My Kindle lay unused for a few days, for the “loaded” book on that was this one, and there was absolutely no enthu to continue reading that. Finally I gave up and moved on to another book.So one point that Vikram Chandra makes in the introduction to the book is that he initially planned to make it a Kindle single, but then decided, upon the urging of his wife and others, to make it into a complete book on coding and poetry. While the intent of writing a full book is no doubt well-placed, the result doesn’t really match up.

For when you try and turn a Kindle single into a full book, you try to add words and pages, and for that reason you write things that aren’t organically attached to the rest of the book. You want to add content, and depth, but instead you end up simply adding empty words – those that you could have done without, and chapters which are disconnected from the rest of the book.

And so it is the case with Vikram Chandra’s Mirrored Mind. There is a whole chapter, for example, on the sociology of the Indian software industry, which is clearly “out of syllabus” for the otherwise excellent novelist, programmer and creative writer Vikram Chandra. He goes into long expositions on the role of women in the Indian software industry, the history of the industry, etc. which are inherently interesting stories, but not when told by Chandra, who is clearly not in his zone while writing that chapter.

And then there is the chapter on Sanskrit poetry, which is anything but crisp, and so verbose that it is extremely hard to get through. There is nothing about code in the chapter, and it is very hard to cut through the verbosity and discern any references to the structure of poetry, and that lays waste to the chapter. It was while reading this chapter that I simply couldn’t proceed, and abandoned the book.

This is by no means a comparison but I’ve gone down this path, too. I’ve written so many blog posts on the taxi industry, and especially on the pricing aspects, that I thought it might make sense to put them all together and convert them into a Kindle Single. But then, as I started going through my posts and began to piece them together during my holiday in Barcelona earlier this year, I got greedy, and I thought I could convert this into a full “proper” book, and that I could become a published author.

And so I started writing, mostly in cafes where I went to for breakfast (croissant and “cortado”) and for coffees. I set myself ambitious targets, of the nature of writing at least two thousand words in each session. This might help me get out a skeleton of the book by the time my vacation ended, I reasoned.

Midway through my vacation, I decided to review my work before proceeding, and found my own writing unreadable. This is not always the case – for example, I quite enjoy going back and reading my own old blog posts. I’m quite narcissistic, in other words, when it comes to my own writing. And I found my own work-in-progress book unreadable! I immediately put a pause on it, and proceeded to fritter away the rest of my vacation in an offhand way.

I got back to Bangalore and sent the “manuscript”, if it can be called such to editor extraordinaire Sarah Farooqui, I don’t know what trouble she went through reading it, but her reaction was rather crisp – that the “book” was anything but crisp and I should cut down on the multitude of words, sentences and paragraphs that added no value. The project remains stillborn.

So based on these two data points, one from a great novelist (none of whose novels I’ve read), and one from my not-so-humble self, I posit that a Kindle single once conceived should be left that way, and authors should not be overcome by delusions of grandeur that might lead them to believe they are in the process of writing a great work. The only thing that can come out of this is a horribly overblown book whose information content is no greater than that of the Kindle single originally conceived.

Long ago on this blog I had written about “blog posts turned into books”, after reading Richard MacKenzie’s book on pricing (Why popcorn costs so much at the movies). The same holds true for Kindle singles turned into books, too. And when I started writing I intended to be a 500-word blog post, not the 900-word monster it has turned into. I wouldn’t blame you if you if you didn’t get this far.

Why VCs continue to fund me-too startups

In a previous post, I had written about how a large number of startups in India are “me-too” companies, and that a sector, once it becomes hot, gets overcrowded. I had also expressed incredulity at the fact that Venture Capitalists continue to fund such “me-too” startups despite knowing that they are copies of companies that exist.

Thinking about it, however, there is one reason that makes the decisions by VCs to fund me-too startups worthwhile – mergers and acquisitions. And this hypothesis is based on M&A activity in the “hyperlocal delivery” (one of those “hot” buzzphrases) space.

Nowadays, due to activity in the sector, the hyperlocal delivery sector has become the equivalent of Pets.com from the turn of the millennium. At a conversation a month ago, for example, a bunch of us weren’t able to fathom how something like Swiggy is valued at what it is, given its decidedly low-tech business of taking packed food from restaurants and delivering it to customers. A couple of months before that, TinyOwl, which is in a very similar business, had raised similar money.

But then two events in the recent (and maybe not-so-recent) past have indicated why VCs continue to invest (and heavily ) in such sectors. Firstly, in February, Foodpanda acquired the Indian operations of Justeat. Both companies are in the business of delivering packed foods from restaurants to people’s homes. And last week, grocery retailer BigBasket acquired Delyver, yet another company in the business of transporting packed food from restaurants to homes.

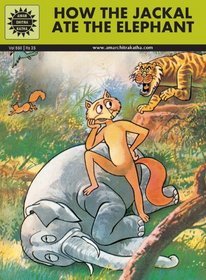
There is this Panchatantra story about a Jackal and a dead elephant. Basically a jackal comes across a dead elephant, and wants to eat it. But for this, he has to fight off other competitors, and also get the elephant’s skin torn in the process. The story involves how he uses different strategies to outwit different animals. Here is a youtube video, not very well made, of this story:

This is the cover of the  Amar Chitra Katha edition where I first came across this story.

And this link has a good summary of the story, all you need to know. Exactly like how it’s in the Amar Chitra Katha story.

The moral I derive from this story in this context is that there are different ways to deal with opponents/competitors. Some opponents you just fight off and finish. Others you learn to coexist with. Yet other you simply “swallow” or acquire. Each of them has its own set of payoffs.

Based on the deals described above, what we notice in the “transport-of-packed-food-from-restaurant-to-homes” business is that companies are preferring to swallow each other (and coexisting with some others) rather than fighting. And when one company acquires another, investors in the target company get a “soft landing”, and don’t lose all of their investment (though it is well possible that the acquisition happens at a valuation lower than that when the investors invested, but ratchets might take care of that).

Apart from investors not losing too much, the advantage of acquisitions is that existing infrastructure of an erstwhile competitor can be leveraged. And when companies are in growth mode and profit and cash are not as important as growth, an acquisition works really well in generating significant inorganic growth. It is a win-win for multiple reasons.

The fact that mergers are the preferred way of getting rid of competition in the startup world puts a cap on the losses an investor might have to bear on an investment (and there are ratchets in any case). And since the downside is now limited, the risk of investing in a me-too startup is significantly lower. In other words, investors invest in a me-too startup since they believe that in the near-worst case it will get acquired rather than shut down. And as a further consequence, there is more incentive for entrepreneurs to set up me-too startups (assuming they can get funded) rather than venturing into virgin territory.

Unions and competition

I completely fail to see why workers’ unions are against competition in the sector. The latest round in this comes from the National Federation for Indian Railwaymen (NFIR), which represents most of the workers in the Indian Railways, which has slammed the Bibek Debroy report on railway restructuring claiming that the report seeks to bring in privatisation into the sector.

Business Standard reports (emphasis mine),

While Debroy has sought to define liberalisation separately from privatisation in the report, he has also said the entry of private players into the system is already provided by extant policy. fear any effort at bringing in private players into railway operations would jeopardise the workers’ jobs and negatively impact railways’ financial health

That private players coming in to railway operations could jeopardise jobs simply defies logic. Currently, the sector has a monopoly employer, namely Indian Railways, and this limits the bargaining power of any worker. With the coming of more (private) players, the demand for skilled workmen is only going to increase, and any new players would be much better off recruiting existing employees of the railways who are experienced in this business than recruiting from elsewhere.

So the coming of private players can only be a good thing from the point of view of workers.


However, what is good for the workers is not necessarily good for workers’ unions. The NFIR is a powerful union, representing 80% of the Railways’ 1.3 million employees (source: Business Standard report quoted above), or about a million employees. With the coming of private players, this number is surely going to go down (thanks to workers leaving, etc.) and this surely cannot be good news for the unions.

In other words, what is good for workers is not necessarily good for unions, and vice versa. And it is important to take this into account while making policy. In popular discourse, workers’ welfare and workers’ unions’ welfare get conflated, leading to policies that are pro unions but (they have higher bargaining powers) but not necessarily pro workers.

Recognition of this distinction can lead to much superior public policy.

Horses, Zebras and Bayesian reasoning

David Henderson at Econlog quotes a doctor on a rather interesting and important point, regarding Bayesian priors. He writes:

 Later, when I went to see his partner, my regular doctor, to discuss something else, I mentioned that incident. He smiled and said that one of the most important lessons he learned from one of his teachers in medical school was:

When you hear hooves, think horses, not zebras.

This was after he had some symptoms that are correlated with heart attack and panicked and called his doctor, got treated for gas trouble and was absolutely fine after that.

Our problem is that when we have symptoms that are correlated with something bad, we immediately assume that it’s the bad thing that has happened, and panic. In that process we don’t consider alternate reasonings, and then do a Bayesian analysis.

Let me illustrate with a personal example. Back when I was a schoolboy, and I wouldn’t return home from school at the right time, my mother would panic. This was the time before cellphones, remember, and she would just assume that “the worst” had happened and that I was in trouble somewhere. Calls would go to my father’s office, and he would ask her to wait, though to my credit I was never so late that they had to take any further action.

Now, coming home late from school can happen due to a variety of reasons. Let us eliminate reasons such as wanting to play basketball for a while before returning – since such activities were “usual” and been budgeted for. So let’s assume that there are two possible reasons I’m late – the first is that I had gotten into trouble – I had either been knocked down on my way home or gotten kidnapped. The second is that the BTS (Bangalore Transport Service, as it was then called) schedule had gone completely awry, thanks to which I had missed my usual set of buses, and was thus delayed. Note that me not turning up at home until a certain point of time was a symptom of both of these.

Having noticed such a symptom, my mother would automatically come to the “worst case” conclusion (that I had been knocked down or kidnapped), and panic.   But then I’m not sure that was the more rational reaction. What she should have done was to do a Bayesian analysis and use that to guide her panic.

Let A be the event that I’d been knocked over or kidnapped, and B be the event that the bus schedule had gone awry. Let L(t) be the event that I haven’t gotten home till time t, and that such an event has been “observed”. The question is that, with L(t) having been observed, what are the odds of A and B having happened? Bayes Theorem gives us an answer. The equation is rather simple:

P(A | L(t) ) =  P(A).P(L(t)|A) / (P(A).P(L(t)|A) + P(B).P(L(t)|B) )

P(B|L(t)) is just one minus the above quantity (we assume that there is nothing else that can cause L(t)) .
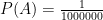
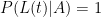
So now let us give values. I’m too lazy to find the data now, but let’s say we find from the national crime data that the odds of a fifteen-year-old boy being in an accident or kidnapped on a given day is one in a million. And if that happens, then L(t) obviously gets observed. So we have

P(A) = \frac{1}{1000000}
P(L(t) | A) = 1

The BTS was notorious back in the day for its delayed and messed up schedules. So let us assume that P(B) is \frac{1}{100}. Now, P(L(t)|B) is tricky, and the reason the (t) qualifier has been added to L. The larger t is, the smaller the value of L(t)|B. If there is a bus schedule breakdown, there is probably a 50% probability that I’m not home an hour after “usual”. But there is only a 10% probability that I’m not home two hours after “usual” because a bus breakdown happened. So

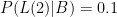
P(L(1)|B) = 0.5
P(L(2)|B) = 0.1

Now let’s plug in and based on how delayed I was, find the odds that I was knocked down/kidnapped. If I were late by an hour,
P(A|L(1)) = \frac{ \frac{1}{1000000} \ 1 }{ \frac{1}{1000000}  \ 1 + \frac{1}{100} \ 0.5}
or P(A|L(1)) = 0.00019996. In other words, if I didn’t get home an hour later than usual, the odds that I had been knocked down or kidnapped was just one in five thousand!
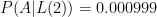
What if I didn’t come home two hours after my normal time? Again we can plug into the formula, and here we find that P(A|L(2)) = 0.000999 or one in a thousand! So notice that the later I am, the higher the odds that I’m in trouble. Yet, the numbers (admittedly based on the handwaving assumptions above) are small enough for us to not worry!

Bayesian reasoning has its implications elsewhere, too. There is the medical case, as Henderson’s blogpost illustrates. Then we can use this to determine whether a wrong act was due to stupidity or due to malice. And so forth.

But what Henderson’s doctor told him is truly an immortal line:

When you hear hooves, think horses, not zebras.

New line of business

I’m considering a new line of business. This is basically advising startups on option valuation and how to account for different conditions and optionalities that venture capitalists put in in term-sheets.

Aswath Damodaran has an extremely interesting piece on valuation of the so-called “unicorns” and how such valuations are inflated on account of optionality in favour of investors. He takes a stab at valuing such optionality, but I think there’s scope for going deeper and helping companies figure out the valuations in each individual case. Money quote from the piece:

As an outsider with an interest in valuation, I find venture capital deals to be jaw-droppingly complex and not always intuitive, and I am not sure whether this is by design, or by accident. When it comes to investor protection, the stories that I read for the most part are framed as warnings to owners about “vulture capital” investors who will use these protection clauses to strip founders of their ownership rights. I think the story is a far more complex one, where both investors and owners see benefits in these arrangements, and where both can expose themselves to dangers, if they over reach.

Do you think this is a good line of business to get into? Will startups be willing to pay for a service that allows founders to get value for money for the equity they are giving away? Or will they be so focussed on execution that trifles such as a change in valuation by a few percentage points don’t matter to them any more?

And what are the odds that if I get into this business and do a good job of it, a VC will want to hire me just so that I stop damaging their carefully designed ratchets?

Slider design

Not often that I comment on User Interface, but this has a quantitative aspect to it, so I thought I’ll write about it. Basically it’s with the use of sliders on websites that you move around to determine an amount or a limit.

More specifically, I’m in the process of planning an extended weekend in Bali next month (the wife is going to be based in Jakarta for two months starting this weekend), and checking out sites such as TripAdvisor and AirBnB for accommodation. This necessarily means using a slider to determine my maximum willingness to pay for a room.

The problem with such sliders is that they’re linear. So for example, on the Travelmob page where I’m looking for villas, the price per night varies from Rs. 650 to Rs. 65000, or a factor of 100. And the slider uses a linear scale. So considering that I consider about Rs. 3500 per night as my budget, in order to set that budget I have to move the right slider (my maximum willingness to pay) way over to the left, till it almost coincides with the left slider (which determines the minimum price). And considering the small distance between the two sliders, it is easy go wrong and not be precise on your limits. A rather frustrating experience!

Instead, if the slider were to use a logarithmic scale, then 6500 would be the midpoint (geometric average of minimum and maximum), and that would allow me to pull the slider to 3500 without much hassle, improving my experience!

But then I suspect the current poor design is by design – by making it hard for you to move sliders down to low prices, maybe they are nudging customers to go for higher priced rooms?

On a different note, while on the topic of sliders, there are “fin-tech” startups that determine whether you are good credit depending upon things like the amount of time you spend moving around a slider to determine how much money you want to borrow. Quoting from Sangeet’s blog:

As an example, most peer lending platforms have a slider allowing the borrower to decide what loan they would like to take. In an excellent whitepaper by Foundation Capital on the state of peer lending, Charles Moldow shares that  the longer a borrower spends moving the slider up and down (and hence, potentially, debating her ability to return the loan), the more likely is she to return the loan. Such correlations help platforms improve their ability to curate participants over time.

This slider also looks linear, rather than logarithmic! And so it goes.

Update

AirBnB actually uses a logarithmic slider! Whatay!

Twitter and Radically Networked Outrage

The concept of Radically Networked Outrage was originally conceived by my Takshashila colleague Pavan Srinath. Having conceived of it, he had promised to blog about it, but it’s been over a month and he’s yet to get down to it. Given this delay, I think I’m justified in stealing this blogpost.

One of the pet themes professed by people at Takshashila, especially Nitin Pai, is the concept of “radically networked societies”. There are too many posts to link to, so I’ll just link to this book chapter that Nitin has written, and to this TEDx talk:

So the whole concept is that societies nowadays are not hierarchical like in the past, but “radically networked”, in that the density of the graph of people in the world has increased significantly with technology. Not only has the density gone up – which means that people are connected to significantly more people than in the past – but technology has enabled people to communicate rapidly.

So you have twitter where you can broadcast your short thoughts. WhatsApp groups enable you to send, and propagate, messages to multiple people at once. This, combined with increased graph density, has resulted in ability for large numbers of people to coordinate and organise, and presents new kinds of governance challenges. For example, it was radically networked societies that resulted in the so-called Arab Spring (which, in hindsight, has mostly led to chaos). Radically networked societies also resulted in the Anna Hazare movement in 2011, which in turn led to the formation of the Aam Aadmi Party, which has taken Delhi by storm.

When societies are so radically networked that they can cause revolutions which can result in the overthrow of governments, they can also such radical networking for lesser causes, such as outraging. When the odd thatha outrages about a certain happening or piece of news, it doesn’t have any impact, and ends up in at best a letter to the editor, and dies a quiet death. If a handful of unconnected thathas outrage about something, it will still not amount to much, and one of their letters to the editor will get published.

However, put together a large number of people densely connected to each other, any outrage in such network will be immediately seen and noticed, and has the potential to go viral. The thing about outrage is positive feedback – when you see someone outraging about a particular topic that you mildly outrage about, you feel encouraged to make your mild outrage public. As the number of people in your network outraging about something increases, the likelihood of you joining in the outrage increases.

So as you can imagine, once there a certain critical mass to outrage about a particular issue, it can go truly viral, until just about everyone is outraging about the topic.

And outrage can have inter-issue positive feedback also. Once you are used to seeing a certain amount of outrage on your twitter timeline, you feel encouraged to make public any marginal outrage about any other issue also. And a number of people getting marginally thus pushed to make their outrage public can result in a further increase in radically network outrage!

We live in a time when societies are radically networked, and outrage is the order of the day. And since outrage causes more outrage, this outrage is unlikely to reduce. It is impossible to say anything remotely controversial on social media nowadays – a pack of outragers will immediately hound you. There are already some victims of such radically networked outrage – like the PR professional Justine Sacco who lost her job after an outraged mob failed to see the humour in her tweet, or scientist James Watson who had to auction his Nobel Prize after outrage about his comments about race had led to speaking assignments dying out, or footballer Ched Evans who is unable to find a club to hire him after doing time for rape. The latest victim of radically networked outrage is Nobel laureate Tim Hunt, who resigned his position as Professor following radically networked outrage about certain remarks he made that were deemed sexist.

And there is no escaping such outrage. In an attempt to escape it, I pruned my Twitter following list a couple of days back, unfollowing people who are highly prone to participate in radically networked outrage. At the end of it, my following list had grown so thin that there was no value for me in Twitter any more. I would just check twitter in the hope of interesting tweets, but come across hardly any tweets.

So today I begin my third sabbatical from Twitter. The first one (January 2014) lasted a month, and the second (August to November 2014) lasted three. I don’t know how long this will last. I’ll be robbed of interesting discussions for sure, but can do without all the negativity prevalent all over my timeline. But I’m sure Radically Networked Outrage will have its way of getting to me again!

In October, during my last sabbatical, I had written about the same topic. And in December, I had written about the “mob courts” of social media.

Uninspiring startups

The other day I suddenly wanted to check out what the “startup scene” is like in India, and so went on to VC Circle, looking at companies that have raised (Series A or B) funding in the last few months. I looked at the last 20 such companies, and quickly got bored. Most of them were in businesses that seemed absolutely uninspiring and banal.

A week ago I was mentioning this to a friend, who chided me for wasting time on VCCircle doing such “research” when Tracxn has it all in one place. And so yesterday, when I was once again in the frame of mind where I wanted to see what’s going on in the startup world. I logged on to Tracxn.

So I couldn’t log on immediately. The site asked me for my “work email” before I could see anything, and when I supplied an email ID that can pass off as a work ID, I got a mail saying it will take some time before I can actually log on. That time turned out to be five minutes, after which I got a message asking me to log on, and I started browsing the section on Indian e-commerce companies.

The experience wasn’t very different from what I had on VCCircle the other day, though evidently this was much quicker and more organised, meaning I could browse more companies with fewer clicks. So I probably got past a hundred startups, not all of them funded (VCCircle reports funding events, so it is biased that way). The tracxn database contains name of company, sector, what their business is, who the founders are (including background), any funding and so forth.

I’m unaware if any biases have crept in to the Tracxn database in terms of listing, but after some cursory viewing, there was a dominant pattern that emerged. And I must admit this is not a pattern that I might have fully appreciated.

So what I found based on the Tracxn database is that most of the startup founders are very young, aged less than 25 (guessing based on their school graduation year). Not too many of them have much in terms of academic pedigree (a few recent IIT graduates here and there, but more the exception than the norm), and not much in terms of work experience (obvious, if you’re starting up before you are 25).

Again the Tracxn data might be biased, but I didn’t find too many technology companies. Most seemed to be of the on-the-ground-getting-things-done kind of businesses. And then there were copycats.

It is not hard to believe, but every time a particular sector gets established or becomes “hot”, it attracts all and sundry. And justifiably so, for the company that might ultimately make money from the sector need not be the pioneer. In fact, there might be a last mover advantage, since the later entrants can learn from the mistakes of the early entrants and set themselves up to succeed better. In that sense the copycats are justified.

But the thing to note is that a large number of such “copycat” companies are getting funded. Some of them might have raised from angels, or small investors, rather than from established Venture Capitalists, but they have obtained financial backing for sure.

Anyways, after my session of looking at startups and analysing them yesterday, the one big insight was that the market is currently rewarding risk taking ability at the cost of all other kinds of abilities. Hot money is chasing startups, so anyone willing to work with a remotely viable idea is able to raise money. How these companies will fan out going forward is anybody’s guess!