More optionality in startup valuations

Mint reports that Indian e-commerce biggies Flipkart and Snapdeal are finding it hard to raise more money at the valuations at which they raised their last funding rounds. One line from the report:

Despite Morgan Stanley’s markdown in February, Flipkart is still approaching investors asking for a valuation of $15 billion, but it hasn’t had any takers yet, the first two people cited above said.

The problem with the valuations is that it includes significant option value. It is common in startup funding to include implicit options in favour of the new round of investors to protect them from the downside of any future decrease in valuation.

Typically designed in the form of “ratchets”, when the firm raises a fresh round at a lower valuation, the investors in the previous round will get additional shares so that their overall share in the investment remains the same (won’t go into the exact mechanics here). This downside protection allows investors to be more aggressive on their valuations of the company, and the company is able to report higher headline numbers.

Ratchets have two problems, both of which are illustrated in the difficulty of Flipkart and Snapdeal in raising more funds. Firstly, optionality in funding means an automatic markdown of funds held by investors in progressively earlier rounds. This is not explicit, but a ratchet is basically existing investors writing an option in favour of the new investors. While the cost of this option is not explicit, it is the earlier investors who bear the cost.

So Series C (and earlier) investors bear the cost of the optionality given to Series D investors. Series B and earlier investors bear the cost of Series C’s optionality. And so on. Notice that this telescopes, so the founders (original owners of equity) have written options to everyone who has invested (of course they also benefit from the higher overall valuation).

Now, if a “down round” (funding round at lower overall valuation than previous round) happens, this optionality gets immediately gets “paid out”. So if the Series D valuation is lower than Series C valuation, Series B and earlier investors (and founders) immediately “pay” the difference to the Series C investors (these options are American, and usually without an expiry date). So Series B and earlier investors (and especially founders) will not like this round. And they will hunt around for offers that will ensure that they don’t have to pay out on the options they’ve written. I suspect this is what is happening at Flipkart and Snapdeal now.

The second problem with ratchets is that stated valuations are inflated. A common share in Flipkart (don’t think one exists. All investors in that firm are effectively either long or short an option in the same stock) is not valued at $15 billion, so that valuation is essentially a misnomer. When Morgan Stanley says on its books that Flipkart is actually worth $11 billion, it is possible that that is the “true value” of the stock, without accounting for the optionality that latest round of investors receive. In other words, the latest round of investors invested at a price, which if extended to all stock, would value the company at $15 billion. But the rest of the company’s stock is not the same as the stock these investors hold! 

The problem, though, is that the latest “headline valuation” (inclusive of optionality) is anchored in the minds of founders and other earlier investors, and they see any lower price as unacceptable. And so the logjam continues. It will be interesting to see how this plays out.

With IPO being way too far off an event for determining if a company has “arrived” I propose a new metric, with shorter horizon. A company can be declared as having arrived if it manages to raise a round of equity with no embedded options. Think about it!

How social media affects your life

My first attempt at writing of any kind was in 2004, when I edited the daily newsletter at Saarang, IIT Madras’s cultural festival. It was a fun experience (I remember digging out my newsletters sometime back, but cant seem to find them now), and I think RAP and I did a pretty good job.

Given that events would go on late into every night and we’d to bring out an edition every morning, some “preprocessing” was key, and I decided to solve the problem through some “online writing” (at the same time I was doing my B.Tech. project in online algorithms, but I digress). As and when I would make a pertinent observation (I borrowed the name for that newsletter, too), I would try and think about how I would describe it in the next day’s newsletter, and immediately jot it down in a notepad I carried.

This way, by the time RAP and I met every evening to compile the newsletter, most of the material would be in place and all we would have to do was to compile, edit and typeset it, and the newsletter would be ready. One time, when we knew that a quiz would go on till dawn (as per tradition), we wrote up the article even before it had happened based on how previous editions had gone. The winner’s name was inserted in the morning just before printing.

The reason I’m telling this story (which I might have told before) is that it inculcated in me the habit of trying to instantly describe in written word anything I saw. Going forward, it became a habit, though it didn’t have much outlet. Later in 2004 I started this blog, and when I would remember the thoughts I’d thought to describe things I saw, I would put it down on this blog.

Twitter changed all that. Now, as soon as I could describe something I saw in a meaningful (and short) fashion, there was an outlet for instant output. Facebook made it even better, allowing me to tell stories with photos and without a word limit (Facebook did photos long before Twitter did). Instagram did the same.

So seven or eight years on social media (I joined Facebook in late 2007 and Twitter in mid 2008) meant that my skill of quick written pertinent observations about just about anything I saw got a lot of encouragement (though, most times no one would react, and at times I would get trolled).

A month after going off social media, I realise that this habit has gotten completely ingrained into me, and irrespective of what I’m doing I’m thinking more about how I’d describe it in a few words (and maybe a picture), rather than enjoying the sight or sound or conversation or whatever! And knowing that I’ve denied myself this mode of output (social media) temporarily, it feels a bit odd when I mentally make one such observation, knowing there’s no way to put it out!

The thing is while I used to already do this before I got access to instant social media, the extent to which I’ve started reacting this way has changed significantly over the years! And I don’t know if that is a good thing.

Anyway, here’s an old style pertinent observation, being made much delayed, and put on this blog (rather than on any other media). I found this place called “ze fork on the water” on the Lake Geneva shoreline yesterday!

zefork

I completed the manuscript of my book

I had set myself an April 15 deadline to finish the first draft of my book, and I’m happy to let you know that I’ve achieved it. This draft weighs in at around 75,000 words, which is probably longer than I’d expected.

Now the hard part begins – of finding publishers, editing, promotions and all that jazz. I don’t even know where to start and which publishers to approach. This is a popular economics book where I use the concept of market liquidity (from finance) to explain why certain markets are structured the way they are, and how markets can be made more efficient.

Here is a brief introduction of the book that I’ve written. I’m yet to give it a name, but the subtitle is “How financial markets explain life”:

Why do people with specialised skills find it hard to switch jobs? Why do transfer fees for footballers always seem either too high or too low? Why are real estate brokers still in business despite the large number of online portals that have sought to replace them?

The answer to all this lies in liquidity. Broadly speaking, market liquidity refers to the ease with which a product or service can be bought or sold in a particular market. With its origins in financial markets, the concept has far-reaching implications in a large number of markets.

In this book, Karthik Shashidhar, a management consultant and public policy researcher, explores a large number of markets, financial and otherwise, and explains why they are structured the way they are. From relationships to property rights, from big macs to public transport, a large number of markets are dissected to show why liquidity remains a useful concept well beyond financial markets where it originated.

Now, while many of the examples are from India, I’ve written this book with a global audience in mind. Hopefully I should be able to publish and sell this book internationally.

There is a full chapter on the economics of Uber, and how surge pricing is critical to creating liquidity in the rides marketplace. There are also chapters on matchmaking, obsolete technologies, agricultural markets and why most Indians cook at home.

I haven’t really seen any other popular economics books from India, so don’t know where to start my publisher hunt. Any leads will be welcome. I’m currently in Barcelona, but will be returning to Bangalore in mid-May.

Oh, and there is very little intersection with this blog, or anything I’ve published so far. One chapter intersects one blogpost here, and another draws from a Mint piece I’ve written, but the rest is all fresh material. So, you people have no excuse but to buy the book when it does come out!

Wish me luck!

Water, IPL and the ease of doing business

The latest controversy surrounding the just-about-to-start ninth edition of the IPL (a court case challenging its staging in Maharashtra while farmers are dying in Vidarbha) is a clear illustration of why the ease of doing business in India doesn’t look like it will improve.

At the bottom of it, the IPL is a business, with the IPL and teams having invested heavily in team building and marketing and infrastructure. They have made these investments so far hoping to recover them through the tournament, by way of television rights, gate receipts, etc.

Now if the courts were to suddenly decide that the IPL should not take place in Maharashtra, it will mean that alternate arrangements will have to be found in terms of venues and logistics, teams which have prepared grounds in Nagpur, Pune and Mumbai will have to recalibrate strategies, and most importantly, the people of these cities who have bought tickets (they clearly believe that the value of these tickets is higher than the price) will also end up losing.

Farmers dying for lack of water is a real, and emotive, issue. Yet, to go after a high-profile event such as the IPL while not taking other simpler measures to curb fresh water wastage is a knee-jerk reaction which will at best have optical effects, while curbing the ability of businesspersons to conduct legitimate business.

There has been much talk about how policy measures such as the retrospective taxation on Vodafone or Cairn have been detrimental to investor sentiment and curbed fresh investments in India. This court case against the IPL days before it began is no different, and a strong signal that India’s policy uncertainty is not going away quickly.

Unless the political class manages to fix this, and provide businesses more stable environments to operate in, it is unlikely we’ll see significant increase in investments into India.

Mike Hesson and cricket statistics

While a lot is made of the use of statistics in cricket, my broad view based on presentation of statistics in the media and the odd player/coach interview is that cricket hasn’t really learnt how to use statistics as it should. A lot of so-called insights are based on small samples, and coaches such as Peter Moores have been pilloried for their excess focus on data.

In this context, I found this interview with New Zealand coach Mike Hesson in ESPNCricinfo rather interesting. From my reading of the interview, he seems to “get” data and how to use it, and helps explain the general over-performance to expectations of the New Zealand cricket team in the last few years.

Some snippets:

You’re trying to look at trends rather than chuck a whole heap of numbers at players.

For example, if you look at someone like Shikhar Dhawan, against offspin, he’s struggled. But you’ve only really got a nine or ten-ball sample – so you’ve got to make a decision on whether it’s too small to be a pattern

Also, players take a little while to develop. You’re trying to select the player for what they are now, rather than what their stats suggest over a two or three-year period.

And there are times when you have to revise your score downwards. In our first World T20 match, in Nagpur, we knew it would slow up,


Go ahead and read the whole thing.

The problem with premium ad-free television

I watched snippets of the just-concluded ICC WorldT20 final using an illegal streaming service, which streamed content drawn from SkySports2.  The horrible quality of the streaming aside (the server seemed to have terrible bandwidth issues), the interesting thing to note was that it was completely devoid of advertisements.

With the quality of cricket coverage in India currently being abysmal due to the frequent cutting for advertisements (I remember getting thoroughly pissed off with the cuts for advertisements before the replay of a wicket was shown during the India-Australia series earlier this year), it made me think about the economics of a separate premium service that is ad-free.

The infrastructure for delivery is in place, given that internet-based legal streaming services are fairly common now (the likes of HotStar). Internet-based delivery also makes it easy to charge pay per view, so payment is also not a problem. This raises the question of whether it is a good idea for channels to monetise the demand for ad-free cricket by providing the service through online streaming, leaving the mainstream broadcast to be monetised via advertisements.

While in theory this appears like a good idea, the problem is with the kind of people who will migrate to the new service – they will be people who have the ability and willingness to pay for a higher quality broadcast. Such people are likely to belong to two overlapping categories – loyal fans of the game and people who can afford to pay a premium.

It is unlikely that the union of these two sets will comprise of too high a proportion of the overall viewership of the game, but the point is that these are the two groups who are likely to be most lucrative to advertisers – the loyal fans watch regularly and the people who are able to pay have more disposable income.

Moving such customers to an ad-free online channel might reduce the supply of advertisements which can be used to reach them, and this might not make advertisers happy. And given that television channels have cosy relationships with advertisers (or at least media buyers), they are unlikely to piss them off by moving the most lucrative customers to a premium platform.

Of course if this segmentation (between ad-free and free broadcasts) is implemented, it will also impact the price of advertisements in the free broadcast. That will need to be taken as an input while setting prices for the ad-free service. In other words, pricing is going to be a challenge!

If some television channel wants to work on this, I’m available for hire as a consultant. I’ve done a fair amount of prior work on pricing and dynamic pricing, am pretty good at quantitative methods and am in the course of writing a popular economics book.

Seasons

This day eleven years back I travelled to London to intern at an investment bank, in the middle of my MBA. The internship was an academic requirement and popularly referred to as “summer internship” at our school. The term confused people in London, though, with the common reaction being “it isn’t summer now”. Over time I learnt to respond to that with “but it’s summer in Bangalore”.

Back when I was a kid I dutifully learnt from textbooks that there were four seasons – “summer, winter, autumn and spring”. Despite efforts of multiple teachers to explain, I could never understand what autumn (there is no mass shedding of leaves in Bangalore) meant. Some Indian books we had substituted “monsoon” for “autumn” and I started assuming that “autumn” referred to the rainy season.

Over time I have understood that the monsoons are a uniquely India-and-around phenomenon, and they don’t exist elsewhere in the world. What’s taken longer for me to understand, however, is how that has affected my understanding of seasons.

Coming from Bangalore, where April is the hottest month, I’ve always assumed “summer” as lasting from March to May. “Mango showers” start coming in in the beginning of May, cooling down things a bit, and by the time we are in June, the monsoon is in full flow and you might even need a light sweater along with your umbrella.

Things heat up mildly again in October, after the South West monsoon has gone, but the sporadic cyclones of the North-East monsoon aren’t too far away, and there’s a graceful transition to winter. And February is the sole month of “spring” before things quickly heat up again.

It’s April already and things are still cold in Barcelona. It’s not as cold on average as a month earlier – I can occasionally dispense with my scarf, and pavement cafes are more full than before. I still need both a sweater and an overcoat, though, and the winds from the Mediterranean mean that the temperature you feel is much lower than what the thermometer suggests.

While I know that things will heat up in Barcelona in the next month (by which time I’ll be preparing to move back to Bangalore), the fact that things are so cold in April, the month I consider to be the peak of summer, is something that makes me terribly uncomfortable. I also find it quite funny that Barcelona was rather warm in October 2014 (when I first visited, and could walk around in shorts) and is so cold now.

This goes to show how much the monsoons affect the seasons in India, and in South India in particular. In fact, the definition of “summer” (as defined by school holidays) is itself different in different parts of India – South India breaks in April and May, and the North (where the monsoon hits much later) in May and June.

And yet, we continue to teach schoolkids that the “four seasons” are “summer, winter, autumn and spring”

PS: I find it hard to reconcile with the six seasons according to the Hindu calendar as well – maybe those have a North Indian bias

On cricket writing

This piece where Suveen Sinha of the Hindustan Times calls out Dhoni’s “joke” with respect to retirement has an interesting tailpiece:

When Dhoni was bantering with the Australian, the other journalists in the hall were laughing. They would, no sports journalist would want to be anything but nice to the formidable Indian captain. That’s why this piece had to be written by someone whose day job is to write on business and economy.

Looking at the reports of the incidents from both Sinha and EspnCricinfo’s standpoints, it is clear to me that Sinha’s view is more logical. That Dhoni’s calling of the journalist to the press conference table and cross-questioning him was unprofessional on the one hand and showed his lack of defences on the other.

Yet, the ending to Sinha’s piece also explains why other sports journalists have taken to lauding Dhoni’s view rather than critisicing him – for them, access to the Indian limited overs captain is important, and they wouldn’t like to damage that by taking an Australian colleague’s side.

The problem with a lot of sports journalism in general, and Indian cricket journalism in particular, is that jingoism and support for one’s team trumps objective reporting and analysis. One example of this was coverage from Indian and Australian newspapers of the Monkeygate scandal in 2007-08 (when Harbhajan Singh called Andrew Symonds a monkey).

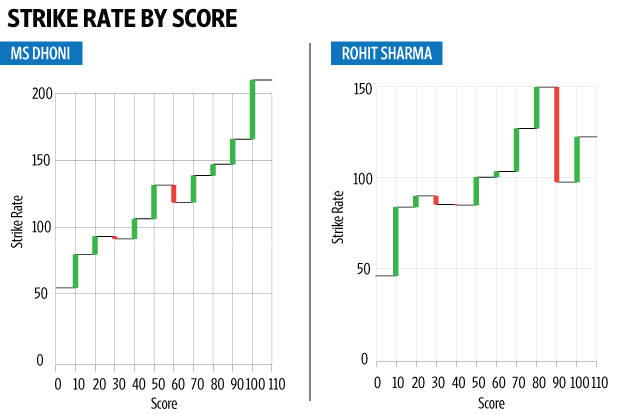
More recently, there was the controversy about India losing games because of the tendency of Rohit Sharma (and Indian batsmen in general) to slow down in their 90s. Again, commentary about that took jingoistic tones, with the Indian sports media coming out strongly in favour of Sharma. There were reports defending his “commitment” and “grit” and all such flowery language sports journalists love, and that Glenn Maxwell’s comment was entirely unwarranted. Maxwell even backed down on his comments.

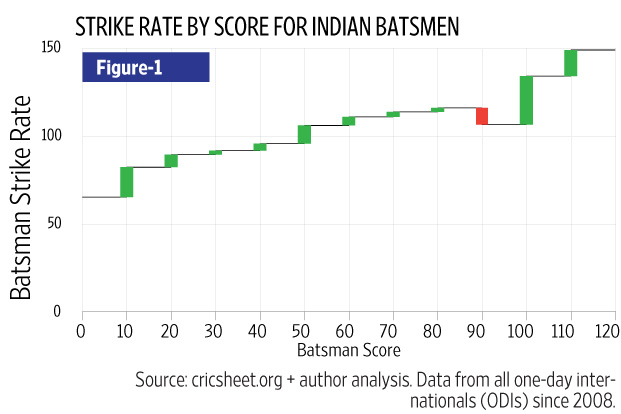
Data, however, showed that Maxwell need not have backed down on his comments. Some analysis based on ball-by-ball data that I published in Mint showed clearly that Indian batsmen do slow down in their 90s, and of all recent players, Sharma was the biggest culprit.

Indian batsmen slowing down in their 90s. My analysis for Mint
Rohit Sharma is among the biggest culprits in terms of slowing down in the 90s

The piece was a hit and was widely shared on social media. What was more interesting, however, was the patterns in which it was shared. For one, the editors at Mint loved it and shared it widely. It was also shared widely by mango people and people with a general interest in cricket.

The class of people which was conspicuous by its absence of commentary on my piece was sports journalists. While it could be reasoned that they didn’t see the piece (appearing as it did in a business publication, though I did send emails to some of them), my reasoning is that this piece didn’t gain much traction among them because it didn’t fit their priors, and didn’t fit the jingoistic narrative they had been building.

It is not necessary, though, that someone only shares pieces that they completely agree with – it is a fairly common practice to share (and abuse) pieces which you vehemently disagree with. The commentary I found about this piece was broadly positive – few people who had shared the piece disagreed with it.

My (untested) hypothesis on this is that this analysis flew in the face of all that mainstream sports journalists had been defending over the previous few days – that Maxwell’s comments were simply not true, or that Sharma was a committed cricketer, and all such hyperbole. With data being harder to refute (only option being to poke holes in the analysis, but this analysis was rather straightforward), they chose to not give it further publicity.

Of course, I might be taking too much credit here, but that doesn’t take away from the fact that there is a problem with sports (and more specifically, cricket) writing. Oh, and as for the ultra-flowery language, I’ll save my comments for another day and another post.


Why authors need convertible debt

At the end of a recent blogpost, I had referred to a piece by Matthew Yglesias where he refers to author advances as “convertible debt”.

 An advance is bundled with a royalty agreement in which a majority of the sales revenue is allocated to someone other than the author of the book. In its role as venture capitalist, the publisher is effectively issuing what’s called convertible debt in corporate finance circles — a risky loan that becomes an ownership stake in the project if it succeeds.

While I agreed with Yglesias’s piece when I had first read it (around the time it was published), I’m not so sure I agree with it now. As I approache the “home stretch” with the first draft of my first book (it’s a popular economics book on liquidity and market design), I’m plunged in self-doubt every time I sit down to write it.

The problem with writing a book is that the author needs to work for months together without any feedback whatsoever. It is occasionally possible for the author to take feedback from a few family members and friends. While such feedback is sometimes useful, the problem is that the people providing the feedback represent only a very tiny fraction of the book’s overall client base (I hope lots of people will read my book once it gets published).

So there is always a reasonable chance that months of effort might result in an absolute dud, implying zero returns. It is also mildly probable, of course, that these months of efforts might result in a blockbuster, but while you are producing it you have no clue which way it will turn out.

This can create serious motivation issues, and on the occasional bad day at work you might be tempted to abandon the project altogether and get back to doing something more predictable. You can have some internal deadlines but they need not be binding (like I’d set the deadline to finish my first draft as the day I went for my vacation to al-Andalus. However I’ve already reneged on that and given myself a further fifteen days). Unless there is extremely strong internal motivation, it is hard to sustain your effort.

This is where convertible debt, in the form of a publisher’s advance, can help. On the upside, the advance will guarantee you some returns (however meagre) from the project. On the downside, the advance from the publisher comes with a deadline, which acts as a Damocles’s sword to ensure you are motivated and finish your book on time.

As a first time author however, whose only published work so far has been 2000 odd posts on this blog and a 100 odd articles for Mint, I didn’t give myself too good a chance of snagging convertible debt, and so I soldier on, hoping my book turns out well.

Soon, once I finish the draft, I hope to start taking the book to publishers. If any of you has leads on who to approach, do let me know. It’s a non-fiction (popular economics) book with an Indian core but written for a global audience. For now I’m ruling out self-publication, since I’m looking at this book as providing me far more than royalty revenues and can do with some publisher validation.

Also, that might help me get some convertible debt for my next book!