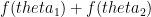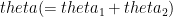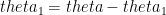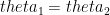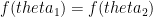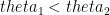Teaching marketing

Recently, the Alumni Association of IIM Bangalore had invited alumni to give interviewing practice to second year students at the institute. This was in an attempt to help them prepare for their “final” placements that are coming up in March. With a view towards brushing up my interviewing skills (haven’t interviewed anyone for close to three years now) and also to check out the kind of people that go to IIM nowadays I decided to volunteer. And ended up interviewing some five or six people.

I had told the organizers that I’d be interviewing for a hypothetical job in my firm and that they should preferably send students with an inclination for “quant” and for consulting. Perhaps there was a mismatch in communication, and perhaps I sent my “requirements” too late, but it so happened that at least half the people who came to were “majoring” in marketing (nowadays they’ve introduced the “major-minor” system at IIMB. If you do five electives from one “area” you “major” in that. Three electives from an “area” gets you a minor. There is no compulsion to either major or minor, though).

Given that the questions that I’d prepared were inclined towards interviewing for a quant/consulting/analytics kind of role (basically whatever I currently do in my “job”), I decided to not veer too far from that while teaching these people. To each of them I put forth a “case”, where the central problem was marketing-related but needed numbers to “solve”. In fact, I made up the case on the spot after one of these students told me he had interned at an e-commerce firm.

So I told them that they are the marketing manager of an e-commerce firm and the firm has launched a few advertising campaigns and now needs to test the effectiveness of such campaigns. I asked them how they would measure this.

Given that they might have just about started off practicing for their placements, I realized they didn’t have much expertise doing “case interviews”, and so tried to help them navigate the case. So for each of them I started by asking them what kind of metric they would use for measuring the effectiveness of the campaigns. And this is the stage that each of their “interviews” came unstuck.

Incredibly, each of them independently started off with “we will first understand what segment this campaign is targeted at”. And then their process of measurement involved identifying a sample of customers of this segment and then “measuring if they had got the intended message of the campaign”. When I told each of them that they weren’t allowed to do a survey, and added for good measure that a focus group discussion is also out of question, they all seemed absolutely lost. I couldn’t really proceed with their cases.

I find it incredible that the three of them (granted – small sample) who are second year students in one of India’s better business schools (at least I hope so) completely failed to imagine that the effectiveness of an advertising campaign can be measured in terms of “sales” or “website hits” or “click through rate” (depending upon the “intended message” of the campaign, one of these becomes the appropriate metric). It seemed to me that their management education had clouded their ability to think intuitively.

In my limited experience in interacting with marketers, I’ve found that a large number of them are fairly resistant to using numbers in their business, and speak in terms not fathomable to the common man (I once made the mistake of applying to a marketing analytics firm, and was promptly sent some questions about measurement of “brand feeling” and such like. I withdrew my application). The impression I get from my small sample is that marketers’ way of thinking is completely divorced from that of other people in business, and have always wondered about why this is. I had assumed it might be a function of getting ingrained into certain marketing jobs, but now it seems like this way of thinking is more deep-rooted.

I was taught core marketing by a somnolent professor who was renowned to be a “great marketer”. He clearly didn’t market marketing too well, for I didn’t take any marketing electives after that. However, I think I “get” related fields such as game theory and behavioural economics, and try to understand marketing using those frameworks. Usually it doesn’t take you too far in a conversation with marketers, though.

Based on my interactions with the three marketing major students I interviewed, it seems to me that something is wrong with marketing teaching, especially at IIMB. It seems to me that marketing is taught as a rule-based discipline, rather than based on first principles. Perhaps that is how recruiters of marketing majors want it to be like, but it seems like this kind of “education” is only going to create poor quality marketers.

PS: I admit to small sample bias, extrapolation and such like.

Understanding different kinds of art

There are some kinds of art that I intuitively understand – like an elegant mathematical proof, or a beautiful combination in a game of chess; a Sachin Tendulkar straight drive, or a long-distance beautifully threaded pass by Xabi Alonso. I can easily appreciate a well-done-up home when I see it. Some music makes me go delirious, and there have been times when I’ve actually started rolling on the floor in ecstasy after listening to certain songs.

But there is art that I simply don’t get. Poetry – for example – I’ve never got what is the big deal with that. To me it just looks like a bunch of sentences broken up in random ways, which is supposed to make it sound nice. In fact, I’ve argued earlier that poetry is a vestige of the pre-writing era.

It is the same with “literature”. Some people read books or articles because they are just “written beautifully”.  I absolutely fail to appreciate that phrase. As long as something is explained simply and intuitively, it is enough for me. In fact, when a writer tries to get too cute and makes a conscious effort to “write beautifully” it puts me off, for it makes the reading less intuitive. As a consequence, there’s hardly any fiction I’ve read in the last 5-6 years.

I was thinking of this last evening when I went to watch this dance show called “Prayog 4” here in Bangalore. I think it was good – the three performances looked extremely well choreographed and well-coordinated, and the dancers seemed to have put in considerable effort into the production. They were all supremely fit and were literally doing gymnastics during the course of the performance. But my appreciation of the performance ended there.

After one of the performances, the wife exclaimed “you know, this dance so represents your and my lives!”. I just couldn’t understand what she was hinting at. All I could see was this one guy dancing round and round in circles, and doing gymnastics on a rope! As I mentioned earlier, his movements were extremely graceful and aesthetically pleasing but I just couldn’t get anything more out of it.

Later last night, my wife asked me what I understood from the first performance (yesterday’s show essentially had three separate performances). “A bunch of chicks doing extremely graceful gymnastics on a bunch of parallel bars”, I replied. “Didn’t you notice how beautifully they represented different emotions during the course of the dance”, she asked. I admitted to recognizing nothing of the sort. Instead, I was sitting there, wondering what the big deal was, and trying to construct this blog post in my head.

“Art” is not unidimensional, and “appreciating art” is too broad a statement. After my experience yesterday I don’t know if there are people who can appreciate all kinds of art. For a moment I thought I was a philistine for I couldn’t appreciate yesterday’s performance, but then I remembered the pieces of art I mentioned in the beginning of this blog post that I truly appreciate. So, no – I’m not a philistine. It’s just that there are certain art forms I get and ones I don’t.

Have you felt similarly sometimes? Are there some art forms you “get” easily, and others that you absolutely fail to get? Or do you consider yourself to be the types that gets all kinds of art, and you argue that the ones you don’t get is simply not art? Or do you fail to get any art at all? Do leave a comment.

ATMs and their security

Paul Volcker, former chairman of the US Federal Reserve and proponent of the Volcker Rule following the financial crisis of 2008 once remarked that the only useful financial innovation in the last twenty years is the ATM. The biggest advantage of the ATM is that because you can get money at any point of time on demand, you don’t need to keep too much of an “emergency stash” at home. For example, you are now extremely unlikely to find more than five thousand rupees in hard currency in my house at any point of time (including my wife’s and my wallets, and our “emergency stash”). In the pre-ATM era, when we would have to wait to visit a bank branch to withdraw money, we would have to keep a much larger sum at home as an emergency fund.

So how does this help the economy? Lesser cash in people’s homes and wallets means more cash in the banking system. Which means that at any given point in time, the banks have more money to lend out, and so the supply of credit is higher, reducing the cost of credit. Reduction in the cost of credit improves investment and thus leads to higher economic growth – which is good for everybody. The ATM is thus pareto-positive in stimulating economic growth.

And this is not all. The presence of the ATM has meant that one of the basic activities for which people would visit bank branches – to withdraw money – has now declined massively. Thus, it is possible for banks to run with much leaner branch infrastructure and this again pays back to the general public in the form of a lower “spread” between the cost of a deposit and the cost of a loan. I read on twitter yesterday (unable to find link now) that the average cost of servicing a customer at a teller counter is Rs. 176 while at an ATM it is Rs. 6. This order of magnitude difference is hard to ignore.

And we are not done yet, for we haven’t yet factored in the ease of drawing money now in the age of the ATM. Ten years back I remember having to wait at the bank branch at IIT for about twenty minutes to withdraw cash. I would have to fill up and submit a form, collect a token and wait till my number was called before I was handed my money. The transaction cost (for the customer) of withdrawing money was way too much. And one had to go during the branch timings. It is all so different now!

Now that we have established that ATMs have a socially and economically useful purpose, let us get to their security. On Tuesday this week in Bangalore a woman was mugged at an ATM when she had gone to withdraw money. The assaulter threatened her with a pistol and a machete, and assaulted her anyway and decamped with her money. The event was caught on the CCTV camera at the ATM and the footage was played out on national television.

http://www.timesnow.tv/India/Woman-attacked-inside-ATM-in-Bangalore/videoshow/4441948.cms

Following this incident the Home Minister of Karnataka has given a directive that banks appoint security guards at ATMs or shut down the ATMs. Initially he gave an ultimatum of three days to implement this rule, but then the impracticality of the suggestion dawned on him and the deadline has now been extended. The question, however, arises on who is responsible for safety of the ATM.

There are two components to safety at an ATM – safety of the cash and safety of the customers who visit it. The cash at the ATM is the bank’s private property, and the bank has chosen to put the cash there (and not somewhere else), so it can be argued that security of the cash inside the ATM machine is the bank’s responsibility. I don’t think there needs to be too much debate on this.

What is debatable, however, is the responsibility of security of people visiting the ATM. The question is if it is the responsibility of the bank or as a public good it is the responsibility of the government. Let us draw an analogy. Let’s say you are visiting my house, and at exactly the same time a robber happens to pay a visit. In the course of the robbery you get injured. Can the state hold me liable for your injury for not securing my house enough against the robbers? Isn’t it the state’s responsibility in the first place that the robbers were on the prowl and they just happened to rob my house when you were visiting?

Public safety is a public good. To get technical, it is non-rival (by keeping the streets safe for you, the streets are also kept safe for me) and non-excludable (having kept the streets safe, you cannot exclude me from enjoying the safe streets). And it being a public good, it is the responsibility of the state to provide it. It also means that it is the responsibility of the state to provide public safety everywhere – be it private or public places. Arguing that the ATM, since it belongs to the bank, is not a public space and hence the state is not responsibility for security there is thus wrong. So the state has no right to demand that banks employ private security guards to guard the ATMs.

So if it is the state’s responsibility to keep ATMs safe does it mean that police be appointed to guard the ATMs? Of course not, for the police’s job is not to guard private property that is the ATM – their job is to ensure public safety. Effective policing would mean that the thug who attacked the woman at the ATM wouldn’t be in business at all, and that he wouldn’t have thought of committing this crime.

So if we don’t have private security guards or cops guarding the ATMs how are we going to keep them safe? I argue that it is a matter of design. If you were to watch the video above, you will notice that the first thing the thug does on entering the ATM behind the victim is to pull down the shutters – thus the happenings of the ATM is shielded from the public eye. If ATMs are by definition perennially open what is the purpose of the shutter? You might also notice in the video that the thug pulled down the shutter once again while exiting. Consequently the victim was found only three hours later and that might have had serious consequences in terms of her health. Would the ATM not be better off without that shutter?

Then, there is the question of whether we need a room at all to house the ATM. Here in India, everywhere except in malls, ATMs have their own rooms, and it was in one such room that the mugging happened on Tuesday. On my few visits abroad, however, I’ve noticed that ATMs there never have their own rooms – they are simply holes in walls on the street from which you can get cash. That automatically puts the ATM in a public space and makes them safer (especially if they are on busy streets). The ATM rooms only provide a false sense of security and can prove counterproductive like in the case we just saw.

As we saw in the first part of this piece, ATMs perform a socially valuable function and it is in the interest of banks to encourage customers to use them. That, however, doesn’t mean that banks appoint guards to all ATMs – there might be an alternate solution that might be cheaper and easier to implement, and it is for the banks to find it. It is NOT the state’s business to mandate how the banks get customers to use their ATMs – the state has to concentrate on maintaining public safety.

In June last year the Reserve Bank of India allowed non-bank entities to run “white label ATMs” – cash dispensing machines that are not affiliated to any banks. The first such ATM came up earlier this year. I’m hopeful that some of these ATM companies will gain enough scale that they can solve the ATM design issue and make them safer and more customer friendly.

Provisioning for Non Performing Assets at Banks

K C Chakrabarty, a Deputy Governor at the Reserve Bank of India recently made a presentation on the credit quality at Indian banks (HT: Deepak Shenoy). In this presentation Dr. Chakrabarty talks about the deteriorating quality of credit in Indian banks, especially public sector banks.

What caught my eye as I went through the presentation, however, was this graph that he presented on “Gross” and “Net” NPAs (Non-Performing Assets). Now, every bank is required to “provision” for NPAs. If I’ve lent out Rs. 100 and I estimate that I can recover Rs. 98 out of this, I need to “provision” for the other Rs. 2 which I expect to become “bad assets”. Essentially even before there is the default of Rs. 2, you account for it in your books, so that when the default does occur, it won’t be a surprise to either you or your investors.

Now, NPAs are measured in two ways – gross and net. Gross NPAs is just the total assets that you’ve lent out that you cannot recover. Net NPAs are gross NPAs less provisioning – for example, if you expected that this year Rs. 2 out of Rs. 100 will not come back, and indeed you manage to collect Rs. 98, then your Net NPA is zero, since you’ve “provisioned” for the Rs. 2 of assets that went bad. If on the other hand, you’ve expected and provisioned for Rs. 2 out of Rs. 100 to be “bad”, and you manage to collect only Rs. 97, your “Net NPA” is Re. 1, since you now have Gross NPA of Rs. 3 of which only Rs. 2 had been provisioned for.

This graph is from Dr. Chakarabarty’s presentation, indicating the movement of total NPAs (across banks, gross and net) over the years:

Source: Presentation by K C Chakrabarty, RBI Dy. Gov. , via Capital Mind

What should strike you is that the net NPA number has always been strictly positive. What this means is that our banks, collectively, have never provisioned enough to offset the total quantity of loans that went bad. I’m not saying that they are not forecasting accurately enough – loan defaults are mighty hard to forecast and it is hard for the banks to get it right down to the last rupee. What I’m saying is that there seems to be a consistent bias in the forecast – banks are consistently under-forecasting the proportion of their assets that go bad, and are not provisioning enough for it. This has been a consistent trend over the years.

This fundamentally indicates a failure of regulation, on the part of both the bank regulator (RBI) and the stock market regulator (SEBI). That the banks are not provisioning enough means that they are misleading their investors by telling them that they are going to have lesser bad assets than actually are there (SEBI). That the banks are not provisioning enough also means that they are exposing themselves to a higher chance (small, but positive) of defaulting on their deposit holders (RBI).

How would this graph look like if the banks were provisioning properly?

The Gross NPA line would have remained where it is, for it doesn’t depend on provisioning. However, if the banks were provisioning adequately, the Net NPA line should have been hovering around zero, going both positive and negative, but mean-reverting to zero! This is because banks would periodically over and under-forecast their bad assets and provision accordingly, and then dynamically change the model. And so forth..

Read the full post by Deepak to understand more about our bank assets.

Eroding Trust in the Indian National Government

The latest issue of The Economist carries an article which talks about the “eroding trust in national governments”. This article is based on a poll conducted by Gallup in 2007 and again in 2012 with one simple question “do you trust your national government?”. World over, the proportion of people answering “yes” to this question has dipped significantly between the two years.

Source: The Economist, Nov 16th 2013


Now, this graph has been sorted by the orange dots (2012 data) so India is lost somewhere in the middle. What if, however, this graph were sorted by the 2007 numbers (white dots)? Notice that the white dot for India is very close to the 90% mark – the highest ever achieved among all countries surveyed in this poll!

This just goes to show the kind of confidence the Indian National Government (UPA-1) enjoyed back in 2007, perhaps a result of the populist schemes it had launched such as the NREGA. This was before any of the scams hit, and this goodwill might have resulted in the government getting voted back into power in 2009. The interesting thing, though, is that the number for India is still higher than that of a large number of OECD countries.

PS: I would have drawn this graph differently. Rather than using a scatter-plot like this, I would have rather used a slope-graph, which would have shown the relative standings in both years and also the way the ratings have moved.


Missed opportunities in cross-selling

Talk to any analytics or “business intelligence” provider – be it a large commoditized outsourcing firm or a rather niche consultant – and one thing they all claim to advise their clients on is strategies for “cross sell”. However, my personal experience suggests that implementation of cross-sell strategies among retailers I encounter is extremely poor. I will illustrate two such examples in this post here.

Jet Airways and American Express together have come up with this “Jet Airways American Express Platinum Credit Card”. Like any other co-branded credit card, it offers you additional benefits on Jet Airways flights booked with this card (in terms of higher points) as well as some other benefits such as lounge access for economy travel. Given that I’m a consultant and travel frequently, this is something I think is good to have, and have attempted to purchase it a few times. And got discouraged by the purchase process each time and backed out.

Now, I’m a customer of both Jet Airways and American Express. I hold an American Express Gold Card (perhaps one of the few people to have an individual AmEx card), and have a Jet Privilege account. Yet, neither Jet or Amex seems remotely interested in selling to me. I once remember applying for this card through the Amex call centre. The person at the other end of the line wanted me to fill up the entire form once again – despite me being already a cardholder. This I would ascribe to messed up incentive structures where the salesperson at the other end gets higher benefits for acquiring a new customer rather than upgrading an existing one. I’ve mentioned I want this card to the Amex call centre several times, yet no one has called me back.

However, these are not the missed cross-sell opportunities I’m talking about in this post. Three times in the last three months (maybe more, but I cannot recollect) I’ve booked an air ticket to fly on Jet airways from the Jet Airways website having logged into my Jet Privilege account and paying with my American Express card. Each time I’ve waited hopefully that some system at either the Jet or the Amex end will make the connection and offer me this Platinum card, but so far there has been response. It is perhaps the case that for some reason they do not want to upgrade existing customers to this card (in which case the entire discussion is moot) but not offering me a card here is simply a case of a blatant missed opportunity – in cricketing terms you can think of this as an easy dropped catch.

The other case has to do with banking. I’m in the process of purchasing a house, and over the last few months have been transferring large amounts of money to the seller in order to make my down payments (which I’m meeting through my savings). Now, I’ve had my account with Citibank for over seven years and have never withdrew such large amounts – except maybe to make some fixed deposits. One time, I got a call from the bank’s call centre, confirming if it was indeed I who had made the transfer. Why did the bank not think of finding out (in a discreet manner) why all of a sudden so much money had moved out of my account, and if I was up to purchasing something and if the bank could help? Of course, later, during a visit to the Citibank local branch recently I found I wouldn’t have got a loan from them anyway since they don’t finance apartments built by no-name builders that are still under construction (which fits the bill of the property I’m purchasing). Nevertheless – the large money transferred out of my account could have been for buying a property that the bank could have financed. Missed opportunity there?

My understanding of the situation is that in several “analytics” offerings there is a disconnect between the tech and the business sides. Somewhere along the chain of implementation there is one hand-off where one party knows only the business aspects and the other knows only technology, and thus the two are unable to converse, leading to suboptimal decisions. One kind of value I offer (hint! hint!!) is that I understand both tech and business, and I can ensure a much smoother hand-off between the technical and business aspects, thus leading to superior solution design.

Landmark mismanagement

Yesterday’s Landmark Quiz in Bangalore was a major waste of time. No, I’m not talking about the quality the quiz here – the prelims was among the better Landmark Quiz prelims I’ve sat through, and given that we just missed out on qualification for the finals (AJMd, as we say here in Bangalore) I didn’t sit through the finals though I was told the questions there too were pretty good.

I’m talking about the transaction costs of attending the quiz. The overall management of the event left much to be desired. First of all, we had to show up at the venue at 11:45 for a quiz that was supposed to start at 1:45 pm. Teams with confirmed seats were let in at around 12:30 and only around 1 o’clock were us “waitlisted” teams let in. There too, the organizers did a major show of letting in waitlisted teams, calling them in order and taking over half an hour to let everyone in.

The point is that even after all the waitlisted teams had been let in, there was plenty of room in the auditorium. This makes me wonder about the wisdom of waitlisting so many teams, and then making such a big show of letting people in. Given that the total turnout was much smaller than the hall capacity, things would have been much simpler if people had been simply left in, with volunteers only ensuring that the seating was efficient (without leaving gaps).

Before the quiz yesterday i started writing a blog post on how the quiz registration process was itself flawed, and gave incentive to people to register zombie teams because the option of registering a team came free. So while the hall had been theoretically filled up many days ago, most of these registrations were zombie registrations thus leading to a long wait list and thus calling people early. Given that the quiz doesn’t have an entry fee, I can’t currently think of a good way to price this option.

But reaching the venue early was not the only waste of time. The written prelims of the quiz finished around 3 pm, including calling out the correct answers. The results, however, weren’t announced till close to 6 o’clock. In the interim time period there was the finals for school students, but that still doesn’t explain why they had to wait until 6 o’clock to announce the results of the senior quiz.

The way I see it, it was sheer disrespect on the part of the organizers of the time of the participants. Yes, Landmark might be a much sought after quiz, rated among the best in the country. Yes, most people come there for the questions and not just to win – and so stay on to watch the finals even when they haven’t qualified (it is indeed commendable that Landmark quizzes have managed to be great spectator events while not dropping quality). Yes, many participants have traveled from other cities and so having traveled the cost of their time might be “cheap” – in that they have little else to do in the rest of the day.

Even taking into account all these, the wastage of 5 hours of each quizzer’s time (2 hours for early reporting; 3 hours gap between prelims and results announcement; 4 if you consider that watching the Junior finals wasn’t a waste of time) is not a done thing. Given the quiz’s unparalleled reputation it is unlikely that market forces are going to tell the organizers that they are wasting people’s time, but the message has to go through.

The Problem With Pie Charts

People don’t seem to get that pie charts are awful. The basic point is that the human eye cannot measure areas as well as it can measure lengths. In order to show this I’ve done some exercises in my workshops – I drew a pie chart and a bar chart and asked the class to estimate the number associated with a particular sector of the pie / particular bar of the bar  graph, and (luckily I must point out, since the class was small) the error in measurement from the class for the pie was more than that of the bar, so I could convince them.

At yet another class I was teaching last weekend, I got another idea to show why pie charts aren’t particularly useful and I thought I’ll share that here.

Check out this pie chart. Let’s say this represents the quantities of various fruits I’ve consumed in the last one year (numbers pulled out of thin air, using the rand() function in Excel). Look at this chart and tell me which fruit I’ve consumed the most and which the least.

You might say that adding data labels might help solve this problem, but my question is if you must add data labels, why have a visualization at all in the first place? Also note the other problem with the pie chart – you need to keep referring to the legend (at least in the default version that Excel offers. I haven’t been able to figure out how to put the category labels next to the pies itself).

How would you better represent this data? Consider this bar chart, in that case, again made using Excel (with a few tweaks to reduce the “ink”). Here, you can clearly see the relative sizes of the quantities of consumption of various fruits, and easily figure out for yourself that my favourite fruit is Orange and least favourite is Grape.

barsample

The basic idea I’m trying to explain is this – there is little that a pie chart can show (apart from proportions, maybe) that a bar chart cannot. And even if you want to show proportions, you can do one additional step of calculating proportions and plotting that in a bar, instead of putting it in a pie.


vso_diwali

Goodhart’s Law and getting beaten on the near post

I would have loved to do this post with data but I’m not aware of any source from where I could get data for this over a long period of time. Recent data might be available with vendors such as Opta, but to really test my hypothesis we will need data from much farther back – from the times when few football games were telecast, let alone “tagged” by a system like Opta. Hence, in this post I’ll simply stick to building my hypothesis and leave the testing for an enterprising reader who might be able to access the data.

In association football, it is more likely for an attacker to have a goalscoring opportunity from one side rather than from straight ahead. Standing between the attacker and the net is the opposing goalkeeper, and without loss of generality, the attacker can try to score on either side of the goalkeeper. Now, because of the asymmetry in the attacker’s position, these two sides of the goalkeeper can be described as “near side” and “far side”. The near side is the gap between the goalkeeper and the goalpost closest to the attacker. The far side is the gap between the goalkeeper and the goalpost on the farther side.

Red dot is goalkeeper, blue dot is striker.


However, my hypothesis is that this has not been the case recently. For a while now (my football history is poor, so I’m not sure since when) it has been considered shameful for a goalkeeper to be “beaten at the near post”. The argument has been that given the short distance between himself and the near post, the goalie has no business in letting in the ball through that gap. Commentators and team selectors have been more forgiving of the far post, though. The gap there is large enough, they say, that the chances of scoring are high anyway, so it is okay if a goalie lets in a goal on that side.

Introductory microeconomics tells us that people respond to incentives. Goodhart’s Law states that

When a measure becomes a target, it ceases to be a good measure.

So with it becoming part of the general discourse that it is shameful for a goalkeeper to be beaten on the near side, and that selectors and commentators are more forgiving to goals scored on the far side, goalkeepers have responded to the changed incentives. My perception and hypothesis is that with time goalkeepers are positioning themselves closer to their near post, and thus leaving a bigger gap towards the far post. And thus, they are not any more optimizing to minimize the total chance of scoring a goal.

But isn’t it the same thing? Isn’t it possible that the optimal position of the goalkeeper for stopping a shot be the same as that of stopping a shot on the near side? The answer is an emphatic no.

Let us refer to the above figure once again. Let us assume that the chance of scoring when the angle is theta be f(theta). Now, we can argue that this is a super-linear function. That is, if theta increases by 10%, the chances of scoring increase by more than 10%. Again we could use data to prove this but I think it is mathematically intuitive. Given that f(theta) is super-linear, what this means is that 1. The function is strictly increasing, and 2. The derivative f'(theta) is also strictly increasing.

So, going by the above figure, the goalkeeper needs to minimize f(theta_1) + f(theta_2). If the total angle available is theta (= theta_1 + theta_2), then the goalkeeper needs to minimize f(theta_1) + f(theta - theta_1). Taking first derivative and equating it to zero we get,
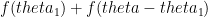
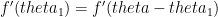
f'(theta_1) = f'(theta - theta_1)

Because f is a super-linear function, we had argued earlier that its derivative is strictly increasing. Thus, the above equality implies that theta_1 = theta - theta_1 or theta_1 = theta_2 or f(theta_1) = f(theta_2).

Essentially, if the goalkeeper positions himself right, there should be an equal chance of getting beaten on the near and far posts. However, given the stigma attached to being beaten on the near post, he is likely to position himself such that theta_1 < theta_2, and thus increases the overall chance of getting beaten.

It would be interesting to look at data (I’m sure Opta will have this) of different goalkeepers and the number of times they get beaten on the near and far posts. If a goalie is intelligent, these two numbers should be equal. How good the goalkeeper is, however, determined by the total odds of scoring a goal past him.