Differential levels of service

On Wednesday I had to send a package to Mumbai by courier. I walked over to the nearby DTDC office and was told that I had two options – i could pay Rs. 85 for “standard courier” or Rs. 180 for “next day guaranteed delivery”.  I asked the guy at the counter when the courier would be “cleared” (i.e. leave the booking office) and he said “this evening”. Assuming that courier gets sent by flight, it would reach Mumbai the next day, so it made me wonder what would take a courier longer to  reach.

I’m reminded of this famous story of HP (or was it Xerox? Or Epson?) adding an additional component to their printer to slow it down so that they could sell it as an “economy model”. The problem with offering differential levels of service in what is essentially the same product is that you know that the service provider has an incentive to willfully offer mediocre service when you go for the cheaper option.

Let us get back to courier, and assume that it is theoretically possible for DTDC to deliver my courier to Mumbai in a day. Suppose they start delivering most “standard” (Rs. 85) packages the following day, then people will have no incentive to go for the “premium” (Rs. 180) service! Because a “premium” service exists, they actually have an incentive to provide poor service for the “standard” package.

It is a similar case with Indigo’s “fast check in” counter at airports. For Rs. 200 you can skip the lines in the airport and go to a special “fast check in” counter. There is the same conflict of interest there – if the regular check in counters were efficient and there were no long lines, there would be no incentive for anyone to go to the “fast check in” counter. So if Indigo has revenue targets for the fast check in counter, it makes sense for them to make the regular check in more inefficient and create longer lines.

Coming back to DTDC, how is the market likely to react to their premium service? Let’s say that I’m someone who regularly sends couriers (but not regularly enough for me to have a deal with DTDC). I’ve been using the “standard” package so far. Most of my letters arrive in Mumbai the next day but a small number (let’s say 10%) take two days to arrive. Now, DTDC introduces the premium package, but I continue using the standard package. What do I see now? Rather than 90% of the letters arriving the next day, only 10% do, and 90% take longer (in line with DTDC’s revised incentives). It is likely that I’ll either start using the premium service or I’ll move to another operator.

The ostensible reason for DTDC introducing an “overnight guaranteed” courier service is easy to see – earlier, 90% of the packages were arriving in a day, and now they guarantee that it is 100%. The problem, however, is that the company will soon want to target increased sales of this “premium” service, and so will start taking steps to prevent the “standard” service from “cannibalizing” the premium sales.

Why the rate of return on insurance is low

I’m currently doing this course on Asset Pricing at Coursera, offered by John Cochrane of the University of Chicago Booth School of Business. I’m about a fourth of the way into the course and the beauty of the course so far has been the integration of seemingly unrelated concepts. When I went to business school (IIM Bangalore) about a decade ago, I was separately taught concepts on utility functions, discount rates, CAPM, time series analysis and financial derivatives, but these were taught as independent concepts without anybody bothering to make the connections. The beauty of this course is that it introduces us to all these concepts, and then shows how they are all related.

The part that I want to dwell upon in this post is the relationship between discount factors and utility functions. According to one of the basic asset pricing formulae introduced and discussed as part of this course, the returns from an asset is a positive function of the correlation between the price of the asset and your expected consumption growth. Let me explain that further.

The basic concept is that one’s utility function is concave. If you were to plot consumption on the X axis and utility from consumption on the Y-axis, the curve would look like this:

In other words, let us say I give you a rupee. How much additional happiness would that give you? It depends on what you already have! If you started off with nothing, the additional happiness out of the rupee that I gave you would be large. However, if you already have a lot of money, then the happiness you would derive out of this additional rupee would be much lower. This is known in basic economics as the law of diminishing marginal utility, and is also sometimes called the “law of diminishing returns”.

So, let us say that tomorrow you will either have Rs. 80 or Rs. 120 (the reason for this difference in payoff doesn’t matter). Let us call these as states “A” and “B ” respectively. Now, suppose I’m a salesman and I offer you two products. Product X  pays you Rs. 20 if you are in state A but nothing if you are in state B. Product Y pays you Rs. 20 if you are in state B and nothing if you are in state A. Assuming that you can end up in states A or B with equal probability, which product would you pay a higher price for?

The naive answer would be that you would be indifferent between the two products and would thus pay the same amount for both. However, rather than looking at just the payoffs, you should also look at the utility of the payoffs. Given the concave utility function, you would derive significantly higher happiness from the additional Rs. 20 when you are in State A rather than in State B (refer to appendix below). Hence, you would pay a premium for product X relative to product Y.

Now, from a purely monetary perspective, the payoffs from X and Y are equal. However, you are willing to pay more for product X than for product Y. Consequently, the expected returns from product X will be much lower than the expected returns from Y (define returns as frac {payoff}{price} - 1. Hence, for the same payoff, the higher the price the lower the returns). Keep this in mind.

Now let us come to insurance. Let us take the example of car insurance. Most of  the time this doesn’t pay off. However, when your car gets smashed, you are compensated for the amount you spend in getting it fixed. What should be your expected return from this product?

Notice that when your car gets smashed, you will need to spend money to get it repaired. So at the time of your car getting smashed, the amount of money (and consequently consumption) is going to be lower than usual. Hence, the marginal utility of the insurance payout is likely to be higher than the marginal utility of a similar payout at a point in time when your consumption is “normal”. This is like product X above – which gives you a payoff at a time when your consumption level is low! And remember that you were willing to expect lower returns from X. Similarly, you should be willing to expect a lower rate of return from the insurance product!

Technical Appendix

A standard utility function used in finance textbooks is parabolic. Let us assume that for a consumption of C, the utility is - (200-C)^2. The following table shows the utility at various levels of consumption:

Consumption          Utility
80  (A)                  -14400
100                        -10000
120  (B)                 -6400
140                        -3600

Notice from the above table that getting the payoff of 20 when you are at A increases your utility by 4400, whereas when you are at B, the payoff of 20 increases your utility by only 2800. Hence, your utility from the payoff is much higher when you are at A than at B. Hence, you would pay a higher price for product X (which pays you when your consumption is low) than product Y (which pays you when your consumption is already high)


The Economics of Forts

I had first planned to write this post back in February 2012, when I visited the magnificent Kumbalgarh Fort in Southern Rajasthan (this was part of my bike ride around that state). However, I didn’t have a typing device handy, so I postponed the post, and it got postponed indefinitely until I visited the equally magnificent Chitradurga Fort in Karnataka recently.

The fort in Chitradurga is famous possibly because of the early 1970s Vishnuvardhan movie Naagarahaavu (cobra) which is set in that city. A lot of the action in the movie takes place in and around the fort, and there is a famous song which is picturized in the fort. The song goes back in history, too, to the battle between Nawab Hyder Ali of Mysore and Madakari Nayaka of Chitradurga back in the 1770s, when after multiple attempts Hyder Ali finally managed to capture the fort. The heroine of the song is one “Onake Obavva” who slays a number of Hyder Ali’s soldiers entering the fort through a small gap in the rocks using her pestle, until she is attacked from behind and killed.

The fort at Chitradurga is popularly known as the “yELu suttina kOTe” or “seven layered fort”. This is not entirely correct. The fort has seven “layers” of walls only on the front side. At  the back, where it is bordered by another hill, there are only two layers of walls. However, the terrain meant that the back was not easily approachable for invaders so most invasions happened through the front. In that sense, the name wasn’t so wrong.

I could write this post about the design of the fort itself (and there is a lot to talk about it -from the rain water harvesting to feed the moats, to the L-shaped design of the gates to the attention to detail in the positions of the soldiers and guards, and arrangements for their camps, and so forth). However, I would prefer here to talk about the economics of building the fort.

The Nayakas of Chitradurga initially started off as a vassal state to Vijayanagara. When Vijayanagara fell in 1565 following defeat at the Battle of Talikota, Chitradurga and the Nayakas became independent. The Nayakas ruled for over 200 years until they were defeated by Hyder Ali in the 1770s. During that period they built this magnificent fort. The question that arises, however, is about how they were able to finance it.

Building a fort with seven layers is no joke. Stones had to be quarried, cut and raised to build each wall. Considerable engineering and architectural acumen also went into the design of the fort itself. It apparently took several generations for the fort to get completed. Considering that there was little economic activity in and around Chitradurga those days apart from agriculture, one can only suppose that the state that built the fort was extractive.

On a visit to Bikaner last February, someone pointed out to me about the quality of the craftsmanship that went into creating the stone carvings in the palace there. “You will never get such quality nowadays”, this person surmised. I agreed with him, and my reasoning was that nobody is willing to pay for such intricacies nowadays. It is only in an extractive state where the taxpayer has no control over the state’s finances that a ruler can spend thus to beautify his own residence rather than spending on the development of the state itself. Where there is a “large coalition” whose support the ruler draws to stay in power, he is forced to invest in projects that benefit this large coalition at the expense of those that just benefit himself.

Wandering through the Chitradurga Fort on Sunday, I thought the expenses on developing the fort could be justified as simply a “large defence budget”. However, the problem with this hypothesis is that a fort doesn’t really provide ‘national security’. What a fort instead does is to make the capital city strong and defensible, but this comes at the cost of securing the borders. People outside the fort are perfectly susceptible to plunder and pillage by the invading party. All the fort does is to protect the capital and the treasury, and thus the king.

The next time you see a magnificent palace or a fort, think of the economic conditions in the state that built it. Think of how the structure might have been financed, and if so much could be spent on a structure such as this what the total size of the royal budget might have been. Then imagine what the tax rates might have been if the royal family managed that large a budget, especially when the kingdom in question was a rather small one like the ones at Chitradurga or Kumbalgarh. Then decide if you would have wanted to live and do business in that age.

After two hundred years of solid resistance, the Chitradurga Fort finally fell to Hyder Ali, in the old fashioned way. Hyder Ali simply bribed some of Madakari Nayaka’s officers, and got them to switch sides. A path through the back that was normally used to supply milk and curd to the fort was discovered, and with the complicity of some of Madakari Nayaka’s officers, Hyder Ali invaded through this route. And the fort fell.

Radhakrishna, the tourist guide who showed us around the fort on Sunday put it best. “Of what use is two walls or seven walls”, he said, “if you can’t exercise control over your own officers?”


What is Takshashila blogging about?

As you might be aware, we run a large number of blogs on the Takshashila platform. I wouldn’t blame you if you might be confused about which blog talks about what. In order to ease your decision-making, we will look at “wordclouds” of each of our bloggers here. As you might be aware, a wordcloud is basically a pictorial representation of the frequency of various words. The more frequently a word appears, the bigger its representation in the wordcloud.

So without much ado, let us go ahead and look at the wordclouds of each of the Takshashila bloggers:

1. Nitin Pai

acorn


2. Pavan Srinath

catalyst3. V Anantha Nageswaran

tgs


4. Rohit Pradhan

retributions


5. Rohan Joshi

filtercoffee


6. Krupakar Manukonda

pratyaya


7. Priya Ravichandransumpolites

8. Sarah Farooqui

terranullius


9. Bibhu Routray

conflictology


10. The Broad Mind (our community blog)

broadmind


11. Logos (the Takshashila Student Blog)

logos


12. Karthik Shashidhar

rq


Measuring Income

Earlier today I was reading an interview in the Business Standard with Shaibal Gupta, Secretary of the Asian Development Research Institute and member of the Raghuram Rajan committee on composite development index of states.  Gupta wrote a dissenting note to the report, with his main contention being the use of the Median Per Capita Expenditure (MPCE) as a measure of income to compare states rather than using the Per Capita Gross State Domestic Product (GSDP). I must state up front that I agree with the report here, and will use this post to defend my stance. Meanwhile, I must mention that one of the reasons he gave for using the GSDP (“Per capita income is taken as an indicator for this purpose by a number of institutions, including the Planning Commission and Finance Commissions.”, he said) almost made me fall off my chair.

Suppose you run a manufacturing company. Your production facility is located in Hosur, Tamil Nadu. However, for administrative convenience, and for the convenience of your top management, you have decided to headquarter your company in Bangalore, Karnataka (for the record, Hosur is just about 35 kms from Bangalore). Most of your workers live in Tamil Nadu, and draw their salaries there. Your top management gets compensated in Karnataka, and they live there. The question is how your company contributes to the economies of the two states.

From an accounting perspective, all your sales are attributed to Karnataka, for you are headquartered there. Of course, what your workers in Tamil Nadu spend out of their salaries will be accounted for in that State’s GDP but the overall sales of the company itself will be attributed to Karnataka, even though the company does next to no economic activity there. With the simple act of locating your company headquarters in Karnataka, you push up Karnataka’s GSDP while reducing Tamil Nadu’s. Some states (eg. Maharashtra and Delhi) are much more popular than others for the location of company headquarters, and they can lead to a fairly distorted figure of how much is produced in each state.

That is not all. The problem with Per Capita GSDP is that it is a mean figure, and is thus liable to be grossly affected by extreme values. Let us say we are comparing the income levels in two neighbourhoods. Neighbourhood A has 1000 people.999 of them earn Rs. 100 per month while the 1000th earns Rs. 1 crore per month. Neighbourhood B also has 1000 people but each of them earns Rs. 10000. Which neighbourhood is richer?

If you go by the mean income, the mean income of A is Rs. (999 * 1000 + 1 * 1,00,00,000)/1000 = Rs. 10999. The mean income of B is Rs. 10000. So you would say that A is richer than B. While on an average that might be true, you might notice that the number for A is skewed by the one rich guy. What this hides is the fact that 99.9% of A earn only a tenth of B’s mean income. Can we do better?

Instead of looking at what the resident of a neighbourhood makes on an average, what if we instead measure what the average person in the neighbourhood makes? In other words, what if we measure the median income in each neighbourhood? The advantage with the median is that it doesn’t get skewed by extreme values, as is likely in case of a variable such as income which usually follows a power law distribution. In our example above, the median income of A is Rs. 1000 while that of B is Rs. 10,000 which is probably a better reflection of the richness of the average resident of these two localities.

Similarly, the per capita GSDP, being a mean measure, is not a great measure for determining the richness or poorness of the people of a state. Suppose, for example, that neighbourhoods A and B are two states. Notice that A will have a much larger GSDP compared to B, and that this tells us nothing about the richness of the average resident of these two states.

Putting both above reasons together, you realize that the per capita GSDP is not  a great estimator of the richness of a particular state.

So what do we use? We discussed above that median income is a much better metric than the mean income. So can we use that for measuring richness instead? While it sounds good in theory, we have a practical and accounting problem – given that a large part of the country is essentially a cash economy, it is hard to keep track of people’s incomes. Moreover, there are enough reasons to both under-report and over-report one’s income if you were to ask someone as part of a survey. For this reason, the general consensus among development economists is that total consumption expenditure is a good estimate of income among the poor, whose net savings rate is negligible.

What about the non-poor, you may ask. Notice that we are only trying to capture the expenditure of the median resident of a state, and assuming that more than 50% of a state is within an income level at which income equals consumption expenditure is fair. So the median per capita expenditure will give a good picture.

So how do we estimate this? Unfortunately, we don’t have any accounting statistics that capture this, and we need to rely on surveys. The National Sample Survey Organization (NSSO) conducts surveys on people’s consumption expenditure every five years, and this is what the Rajan committee has used. Now, you may question the wisdom of relying on sample data (rather than “population data”) to determine the richness or poorness.

The answer to that is that the median is a rather robust statistic, and as long as samples have been chosen at random, it is unlikely that the median of a sample will be too far away from the median of the population (and this is independent of the distribution of the population). We will examine the issue of sampling median in a subsequent post.

In conclusion, I endorse the decision of the Rajan committee to use the median per capita consumption expenditure as a metric for determining the richness or poorness of a state.

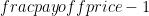
Correlations: In Traffic, Mortgages and Everything Else

Getting caught in rather heavy early morning traffic while on my way to a meeting today made me think of the concept of correlation. This was driven by the fact that I noticed a higher proportion of cars than usual this morning. It had rained early this morning, and more people were taking out their cars as a precautionary measure, I reasoned.

Assume you are the facilities manager at a company which is going to move to a new campus. You need to decide how many parking slots to purchase at the new location. You know that all your employees possess both a two wheeler and a car, and use either to travel to work. Car parking space is much more expensive than two wheeler parking space, so you want to optimize on costs. How will you decide how many parking spaces to purchase?

You will correctly reason that not everyone brings their car every day. For a variety of reasons, people might choose to travel to work by scooter. You decide to use data to make your decision on parking space. For three months, you go down to the basement (of the old campus) and count the number of cars, and you diligently tabulate them. At the end of the three months, you calculate that on an average (median), thirty people bring their cars to work every day. You calculate that on ninety five percent of the days there were forty or fewer cars in the basement, and on no occasion did the total number of cars in the basement cross forty five.

So you decide to purchase forty car parking spaces in the new facility. It is not the same set of people who bring their cars to work every day. In fact, each employee has brought his/her car to the workplace at least once in the last three months. What you are betting on here, however, is correlation, You assume that the reason Alice brings her car to office is not related to the reason Bob brings his car to office. To put it statistically, you assume that Alice bringing her car and Bob bringing his car are independent events. Whether Alice brings her car or not has no bearing on Bob’s decision to bring his car, and vice versa. And you know that even on the odd day when more than forty people bring their cars, there are not more than forty five cars, and you can somehow “adjust” with your neighbours to borrow the additional slots for that day. You get a certificate from the CEO for optimizing on the cost of parking space.

And then one rainy morning things go horribly wrong. Your phone doesn’t stop ringing. Angry staffers are calling you complaining that they have no place to park. Given the heavy rains that morning, none of the staffers have wanted to risk getting wet in the rain, and have all decided to bring their cars. Never before have they faced a problem parking so they are all confident that there will be no problem parking once they get to work, only to realize there is not enough parking space. Over a hundred employees have driven to work, and there are only forty slots to park.

The problem here, as you might discover, is that of correlation. You had assumed that Alice’s reason to get her car was uncorrelated to Bob’s decision. What you had not accounted for was the possibility that there could be an exogenous event that could suddenly drive the correlation from zero to one, thus upsetting all your calculations!

This is analogous to what happened during the Financial Crisis of 2008. Normally, Alice defaulting on her home loan is not correlated with Bob defaulting on his. So you take a thousand such loans, all seemingly uncorrelated with each other and put them in a bundle, assuming that 99% of the time not more than five loans will default. You then slice this bundle into tranches, get some of them rated AAA, and sell them on to investors (and keep some for yourself). All this while, you have assumed that the loans are uncorrelated. In fact, the independence was a key assumption in your expectation of the number of loans that will default and in your highest tranche getting a AAA rating.

Now, for reasons beyond your control and understanding, house prices drop. Soon it becomes possible for home owners to willfully default on their loans – the value of the debt now exceeds the value of their home. With one such exogenous event, correlations suddenly rise. Fifty loans in your pool of thousand default (a 1 in gazillion event according to your calculations that assumed zero correlation). Your AAA tranche is forced to pay out less than full value. The lower tranches get wiped out. This and a thousand similar bundles of loans set off what ultimately became the Financial Crisis of 2008.

The point of this post is that you need to be careful about assuming correlations. It is to illustrate that sometimes an exogenous event can upset your calculations of correlations. And when you go wrong with your correlations – especially those among a large number of variables, you can get hurt real bad.

I’ll leave you with a thought: assuming you live in a primarily two wheeler city (like Bangalore, where I live), what will happen to the traffic on a day when 10% more people than usual get out their cars?

Trying to understand the Telangana situation

Let me state at the outset that this is a dispassionate outsider’s perspective. It’s also rather abstract – I don’t really care about the emotional factor behind the split or the non-split, or how Andhra Pradesh came into being. All that, in my opinion, is secondary.

So the basic issue is this. There is the state of Andhra Pradesh. One part of the state (a minority) thinks it will be better off being a separate state. So for years now they have been clamouring for a separate state. The rest of the state doesn’t want to let them go. And so we have a deadlock.

Let us go back to 2000, when three new states were created in India, breaking up Uttar Pradesh, Madhya Pradesh and Bihar. Those three states also had long-standing demands for separation. All those states had seen “movements” to that effect. The emotional factor was high. The key point, however, is that in each of those states, the rest of the state willingly let go of the breakaway part. Each of the three assemblies passed resolutions recommending the breakaway states. So finally when those states were created the process was rather peaceful and amicable.

That is not happening in Andhra. The Rest-of-Andhra is unwilling to let go of Telangana. Politicians across parties think a breakaway Telangana is a bad idea. The Andhra Pradesh assembly is unlikely to pass a resolution recommending the split any time in the near future. Right now the central government is trying to bulldoze the split and we are seeing the chaos that we are. The question is how we can do this better.

What helped the formation of Uttarakhand, Jharkhand and Chhattisgarh is that their geography is very different from that of their parent states. More importantly, these three states have the kind of geography that makes it hard to govern them. Hilly or forested tracts, with slow transportation and underdeveloped roads meant that administering these areas was costly. Essentially if you did a cost-benefit analysis it made sense to let go of these states – it made the job of the original state government administratively easier.

The problem with the Andhra split is that the capital city Hyderabad lies in smack in the middle of the region that wants to breakaway. People from Rest-of-Andhra have invested heavily in the city, and fear for their investments in case it becomes part of a separate state. It doesn’t help matters that people from Telangana and from the Rest-of-Andhra don’t particularly trust each other. The former claim that the latter have been persecuting them, and the latter fear the same in case the former get their own state. Events over the last few months have only made this trust deficit significantly worse.

What needs to happen is that Telangana needs to assure the Rest-of-Andhra that the people in the latter won’t lose out due to the state split. One way to do this is to sweeten the deal in terms of Hyderabad. One option that had come up would have made Hyderabad a union territory, thus putting it outside the control of Telangana. Another would be for Rest-of-Andhra to be assured of an annual payment based on the state taxes raised from Hyderabad city. This, however, is unlikely to work given the lack of mutual trust.

There is a third option – which is what is being played out now. Telangana acts as a tough guy, and a bully. One who will bully its way into getting its own state. The way this is probably going to work is that by continuously rioting in Hyderabad, it will force businesses to leave the city. As things get worse, the economic value of the city of Hyderabad fall so much that Rest-of-Andhra see no value in holding on to it and vote for the resolution to split the state. Of course, this is not good for anyone since this involves value destruction, but this seems the way things are headed right now.

What might also work (destructive, but not as much as the above) is for Rest-of-Andhra to get a strong message that the state is going to be split sometime in the near future and they have no say in it (this is probably the Central Government’s message currently). Currently, people from Rest-of-Andhra are hopeful that the split won’t happen and are thus holding on to their investments in Hyderabad. As there is more conviction that the state is going to split, they will start slowly withdrawing their investments, so that at  some point in the near future, there will be enough politicians from Rest-of-Andhra that will vote in favour of the split in the state.

Note that not all legislators from Rest-of-Andhra need to support the state split. Telangana contains 119 out of the 294 seats in the Andhra Assembly. Assuming that there is bipartisan support for the split among Telangana MLAs, they need the support of only 29 more legislators to have their way. Of course there is the Anti-Defection Law and all that, but this is some food for thought.

Lastly, I don’t think the current process of the Union Government bulldozing the state split is going to work out in the long term. You don’t want to have neighbouring states that mistrust each other. Yes, Andhra Pradesh is a vast state and might be tough to administer. But no decision on its split should be taken without the resolution by its own assembly.

Charting in Excel

Pavan Srinath, my colleague at the Takshashila Institution, referred to me this excellent tutorial on charting in Excel. It’s been a while since I made too many charts in Excel, since I find the defaults rather irritating and manipulation rather difficult. I make most of my charts using R. I like the command line interface. I like the fact that I have full control over my charts and that I can customize it the way I want (and with a dozen characters of code make it look like a chart from The Economist or The Wall Street Journal).

However, I realize R is a specialized tool and not everyone will want to use it. Hence, at least for the purpose of teaching visualization, I need to learn to chart on Excel. The link above is excellent, and has some good tips on visualization also (for example – on not using 3D charts and not using multiple Y axes). I’m not including any excerpt here since I think anything less than the full post will not do justice to it.

Blossom, not babykutty

I wouldn’t be wrong in saying that most of the books I own have been bought at Blossom, the new and secondhand bookstore on Church Street, Bangalore. I have bought significantly from Premier Bookshop also, but there was an inflexion point in my reading after Premier closed, so most of my book-buying has happened after that. I have bought some books from larger stores such as Landmark or Crossword, but they are too few to be counted. In fact, I would hate to classify Landmark or Crossword as “bookstores” any more, given the amount of real estate they allocate for that trade.

So I was at Blossom last month, browsing its shelves. The Karnataka Quiz Association still gives out its prizes in the form of Blossom coupons, and since I still have a few unspent coupons, I was at the store looking if there was a book I liked. And possibly for the first time ever in that store, I was underwhelmed.

Essentially my book buying and reading habits have changed significantly in the last two years (my last “raid” on Blossoms was in September 2011). Sometime in 2012 i got myself a Kindle. While I initially used it to read PDFs and free e-books and instapaper, I soon warmed up to buying books directly from the Kindle store. The gamechanger as far as I was concerned was the free samples. You can download free samples of any e-book on your Kindle, and once you’ve read the sample (typically about 7% of the book) you can purchase the book with a single click (from your Kindle itself). Some of the books which I’ve wanted to explore have had me so hooked that I’ve ended up buying. And now (partly as a result of a weak ligament in my left thumb) I find it hard to read physical books!

The primary reason I felt underwhelmed at Blossom was that my process for book-discovery has also changed, along with my process for book buying. One of the advantages buying regularly from Amazon is that their recommendation engines start working for you. So nowadays, if I want to browse books, i go to the Amazon website and start looking through my recommendations. And so far, I’ve bought a few of my recommended books and have ended up liking them.

Being a regular visitor to the Amazon recommendations page means that I’m clued in to the long tail of books, which would happen earlier only when i visited special bookshops such as Blossom. Also, the breadth of Amazon’s collection means that I’m more likely to find a title I like on the Kindle Store than in a bookshop like Blossom. And add to this my preference for ebooks over physical books and you know why Blossom doesn’t pleasure me any more.

So every time I would look through the shelves on the third floor of the store (the non-fiction section housing secondhand books) and find something interesting, I would find myself reaching for my phone and checking if the book were available on the kindle store. I would contemplate buying the book only if it weren’t available on the Kindle store or if it  were extraordinarily priced.

I had gone to Blossom with about a thousand rupees of coupons (collected over various quizzes) but was able to spend only half of them. Solstice at Panipat (about the third battle in 1761) wasn’t available on the Kindle Store. It was a similar story with KA Nilakanta Sastri’s The History of South India. Jane Jacobs’ Cities and The Wealth Of Nations was available on the Kindle Store but the Blossom price was too tempting.

I realize that despite my binge on the Kindle Store, I have more unread physical books than e-books. I wish some day Amazon were to come up with a program where I could exchange physical copies of my books for ebooks. That way I’m sure I would read more.

Studying on coursera

In the last one year or more I’ve signed up for and dropped out from at least a dozen coursera courses. The problem has been that the video lectures have not kept me engaged. I seem to multitask while watching these videos, and the sheer volume of videos in some of these lectures has been such that I’ve quickly fallen behind, and then lost interest. I must, however, admit that many of these courses haven’t been particularly challenging. In courses such as “model thinking” or “social network analysis” I’ve already known a lot of the stuff, and thus lost interest. Modern World History (by Philip Zelikow ) was more like an information-only course which I could have consumed better in the form of a book.

Given that I’ve had bursts of signing up for courses and then not following up on them, for the last six months I’ve avoided signing up for any new courses. Until two weeks back when, on a reasonably jobless evening during a visit to my client’s Mumbai office, I decided to sign up for this course on Asset Pricing. And what a course it has been so far!

I went to bed close to midnight last night. I watched neither the Champions League final nor Arsenal’s draw at West Brom. I was doing my assignments. I spent three hours on a Sunday evening doing my assignments of the coursera Asset Pricing course, offered by Prof John Cochrane of the University of Chicago.

I’ve only completed the assignments of “Week 0” of the eight-week long course, and have watched the lectures of “Week 1” and I’m hooked already. I must admit that nobody has taught me finance like this so far. In IIM Bangalore, where I got my MBA seven years ago, we had a course on microeconomics, a course on corporate finance and a course on financial derivatives (elective). The problem, however, was that nobody made the links between any of these.

We studied the concept of marginal utility in Economics, but none of the finance professors touched it. In corporate finance, we touched upon CAPM and Modigliani-Miller but none of the later finance courses referred to them. There was a derivation of the Black-Scholes pricing model in the course on derivatives, but that didn’t touch upon any other finance we had learnt. In short, we had just been provided with the components, and nobody had helped us connect it.

The beauty of the Chicago course is that it is holistic, and so well connected. The same professor, in the same course, teaches us diffusions while in another lecture uses the marginal utility theory from economics to explain the concept of interest rates. In an assignment he has got us to do regressions and in some others we do stochastic calculus. Having seen each of these concepts separately, I’m absolutely enjoying all the connections, and that is perhaps helping me keep my interest in the course.

And it is a challenging course. It is a PhD level course at Chicago (current students at the university are taking the course in parallel with us online students) and my complacency was shattered when I got 3.5 out of 11 in my first quiz. It assumes a certain proficiency in both finance and math, and then builds on it, in a way no finance course I’ve ever taken did.

Also what sets the course apart is the quality of the assignments. Each assignment makes you think, and make you do. For example, in one assignment I did last night I had to do a set of regressions and then report t values and R^2s. In another, I had to plot a graph (which I did using excel) and then report certain points from the graph. Some other assignments make sure you have internalized what was taught in the lectures. It has been extremely exciting so far.

Based on my experience with the course so far, I hope my enthusiasm will last. I don’t know if this course will help me directly professionally. However, there is no doubt that it keeps me intellectually honest and keeps me sharp. I might not have had the option to take too many such courses during my formal education. I hope i can set this right on Coursera.